BTW, DOWNLOAD part of ITPassLeader AFP-Exam-1 dumps from Cloud Storage: https://drive.google.com/open?id=1QBlhG4BHOhW66WJys8EfZYHcccdfce2x
Briefly speaking, our AFP-Exam-1 training guide gives priority to the quality and service and will bring the clients the brand new experiences and comfortable feelings. For we have engaged in this career for years and we are always trying our best to develope every detail of our AFP-Exam-1 study quiz. With our AFP-Exam-1 exam questions, you will find the exam is just a piece of cake. What are you still hesitating for? Hurry to buy our AFP-Exam-1 learning engine now!
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
| Technical Competencies | 84% | - Tax Planning - Retirement Planning - Estate Planning - Investment Planning - Asset and Liability Management - Risk Management and Insurance |
>> AFP-Exam-1 Latest Exam Tips <<
Do you want to choose a lifetime of mediocrity or become better and pursue your dreams? I believe you will have your own pursuit. Perhaps you do not know how to go better our AFP-Exam-1 learning engine will give you some help. The choice is like if a person is at a fork, and which way to go depends on his own decision. Our AFP-Exam-1 Study Materials have successfully helped a lot of candidates achieve their certifications and become better. Our AFP-Exam-1 learning guide will be your best choice.
NEW QUESTION # 37
How should Jenny, a financial planner, explain the benefits of a fee for service method of compensation to a prospective client?
Answer: A
Explanation:
A fee-for-service model reduces the incentive to recommend one product over another because compensation is not driven by product commission. The planner is paid for advice, planning work, or an agreed service arrangement rather than the compensation embedded in a product sale. This does not guarantee perfect objectivity, but it directly addresses product-compensation bias and makes remuneration more transparent.
Option A is not the benefit; charging more because products are complex can create its own conflict if not disclosed. Option B describes performance-based compensation, not fee-for-service financial planning.
Option C is imprecise because compensation is not objectively determined by the quality of the financial plan; it is determined by the fee arrangement. Jenny should explain the model in terms of transparency, alignment, and reduced product-driven incentives. Study Guide focus: planner compensation, fee-for-service advice, conflicts of interest, disclosure, and client relationship management. The compensation discussion should occur before engagement so the client understands what is being paid and why.
NEW QUESTION # 38
Alexis has an index-linked GIC with an adjusted cost base of $20,500. The GIC was issued one year ago, has four years remaining to maturity and provides her with 60% participation in the gains of the S & P/TSX 60 Index, based on the level of the Index at maturity or at redemption prior to maturity. The GIC has a 2% fee if redeemed in the first two years. Alexis notices that the S & P/TSX 60 Index is up 25% and she would like to redeem her GIC. She asked her financial planner if she redeems her GIC, how much she would receive upon redemption. What will her financial planner tell her?
Answer: A
Explanation:
The redemption calculation follows the participation formula and then applies the early redemption fee.
Alexis's adjusted cost base is $20,500. The S & P/TSX 60 is up 25%, and the GIC gives her 60% participation, so the credited gain is 15% of principal. That brings the value to $23,575 before charges.
Because the GIC is redeemed during the first two years, the 2% fee applies. Two percent of $23,575 is
$471.50, leaving approximately $23,104 after the fee. Option B ignores the participation cap and uses the full index gain. Option D calculates the participation gain but ignores the redemption charge. Option A ignores the positive index-linked value. This question tests structured-product mechanics: index participation does not equal full market exposure, and liquidity before maturity may carry explicit cost. Study Guide focus: index- linked GICs, participation rates, early redemption fees, ACB, and investment liquidity. The adviser should also explain that index-linked guarantees protect principal differently from direct equity ownership.
NEW QUESTION # 39
In order to increase the assets in Rebecca's retirement savings, her financial planner is considering making a number of recommendations. Prior to obtaining her current employment, she withdrew funds from her RRSP under the Lifelong Learning Plan to upgrade her skills. She has four annual installments remaining on her Lifelong Learning Plan withdrawal and a small amount of savings in a TFSA. Rebecca now works as a sales associate in a small clothing store that has a group RRSP program for all employees which matches employee contributions. Which recommendation provides the best long-term impact to grow her retirement savings?
Answer: D
Explanation:
The company group RRSP match is the strongest long-term retirement recommendation because it provides immediate additional savings from the employer. A matching contribution is effectively a guaranteed enhancement to Rebecca's retirement funding that she cannot replicate by simply transferring her TFSA or changing her asset mix. Repaying the Lifelong Learning Plan installments is required, but it does not create new employer-funded retirement capital. Maximizing equity exposure may improve expected return, but it must remain within risk tolerance and does not replace the value of free matching contributions. Transferring TFSA savings to an RRSP may produce a deduction, yet it sacrifices TFSA flexibility and does not address the employer match. The AFP planning priority is to capture available employer contributions first, then coordinate LLP repayments, TFSA use, and ongoing RRSP savings. Study Guide focus: group RRSPs, employer matching, LLP repayment, retirement accumulation, and savings prioritization. Missing the match would leave employer money unclaimed, which is rarely defensible when the employee can afford the contribution.
NEW QUESTION # 40
Dianna has just taken a 20-year mortgage and wants insurance only to ensure the mortgage can be repaid if she dies during that period. She is considering whole life insurance. What should her planner most likely explain?
Answer: C
Explanation:
The need described is temporary: repay a mortgage if death occurs during the 20-year amortization or term horizon. Term life insurance is usually designed for exactly this type of time-limited risk. It provides a death benefit for a selected period and is typically less expensive than permanent insurance for the same initial coverage amount. Option A is inaccurate because whole life includes lifetime coverage and cash-value features, which increase cost and may be unnecessary for a temporary debt. Option C confuses mortgage default insurance, which protects the lender against borrower default, with life insurance that protects the family's cash flow. Option D is wrong because critical illness insurance pays on survival after a covered illness; it does not pay a death benefit. The planner should compare personally owned term insurance with creditor insurance, considering underwriting, beneficiary control, portability, and conversion privileges. The recommendation should match the liability duration and the client's broader survivor-income needs.
References/topics: term life insurance, mortgage protection, temporary insurance needs, risk management.
NEW QUESTION # 41
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: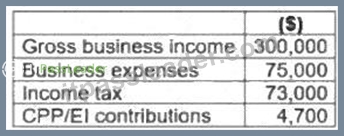
What is Terry's net business income?
Answer: B
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 42
......
Using ITPassLeader you can pass the CSI AFP-Exam-1 exam easily. The first time you try to participate in CSI AFP-Exam-1 exam, selecting ITPassLeader's CSI AFP-Exam-1 training tools and downloading CSI AFP-Exam-1 practice questions and answers will increase your confidence of passing the exam and will effectively help you pass the exam. Other online websites also provide training tools about CSI certification AFP-Exam-1 exam, but the quality of our products is very good. Our practice questions and answers have high accuracy. Our training materials have wide coverage of the content of the examination and constantly update and compile. ITPassLeader can provide you with a very high accuracy of exam preparation. Selecting ITPassLeader can save you a lot of time, so that you can get the CSI AFP-Exam-1 Certification earlier to allow you to become a CSI IT professionals.
AFP-Exam-1 Latest Exam Vce: https://www.itpassleader.com/CSI/AFP-Exam-1-dumps-pass-exam.html
BTW, DOWNLOAD part of ITPassLeader AFP-Exam-1 dumps from Cloud Storage: https://drive.google.com/open?id=1QBlhG4BHOhW66WJys8EfZYHcccdfce2x