What's more, part of that Prep4sureGuide IIA-CIA-Part3 dumps now are free: https://drive.google.com/open?id=1c0cPiqfZJUodY1x_PDA-nCvh0A0OcQT-
It is browser-based; therefore no need to install it, and you can start practicing for the Internal Audit Function (IIA-CIA-Part3) exam by creating the IIA IIA-CIA-Part3 practice test. You don’t need to install any separate software or plugin to use it on your system to practice for your actual Internal Audit Function (IIA-CIA-Part3) exam. Prep4sureGuide Internal Audit Function (IIA-CIA-Part3) web-based practice software is supported by all well-known browsers like Chrome, Firefox, Opera, Internet Explorer, etc.
| Section | Objectives |
|---|---|
| Information Security and Business Continuity | - Information security management principles - Data protection and privacy considerations - Business continuity and disaster recovery |
| Information Technology and Business Systems | - IT controls and cybersecurity fundamentals - Information systems and data governance - System development lifecycle concepts |
| Financial Management | - Managerial accounting concepts - Budgeting and cost control - Financial statements and reporting basics |
| Risk Management and Regulatory Environment | - Internal controls and governance concepts - Compliance and regulatory frameworks - Enterprise risk management (ERM) principles |
| Business Acumen and Global Business Environment | - Global business environment and market influences - Organizational structure and business processes - Business strategies and objectives alignment |
>> Reliable IIA-CIA-Part3 Exam Pattern <<
The page of our IIA-CIA-Part3 simulating materials provides demo which are sample questions. The purpose of providing demo is to let customers understand our part of the topic and what is the form of our IIA-CIA-Part3 study materials when it is opened? In our minds, these two things are that customers who care about the IIA-CIA-Part3 Exam may be concerned about most. We will give you our software which is a clickable website that you can visit the product page.
NEW QUESTION # 511
Which of the following attributes of data are cybersecurity controls primarily designed to protect?
Answer: B
Explanation:
Cybersecurity controls are primarily designed to protect the Confidentiality, Integrity, and Availability (CIA) of data. These are the three fundamental principles of cybersecurity and are essential for protecting organizational information assets. Let's analyze each option:
Option A: Veracity, velocity, and variety.
Incorrect. These attributes are commonly associated with big data and data analytics rather than cybersecurity.
Cybersecurity controls focus on ensuring that data is secure, rather than on its volume, speed, or diversity.
IIA Reference: Cybersecurity risk management frameworks emphasize the CIA triad over big data attributes.
(IIA GTAG: Auditing Cybersecurity Risk)
Option B: Integrity, availability, and confidentiality.
Correct. These three principles are at the core of cybersecurity:
Confidentiality: Ensures that sensitive information is only accessible to authorized individuals.
Integrity: Protects data from unauthorized modifications or corruption.
Availability: Ensures that data and systems are accessible when needed.
IIA Reference: The IIA's guidance on IT governance highlights the CIA triad as the foundation of cybersecurity. (IIA GTAG: Information Security Governance) Option C: Accessibility, accuracy, and effectiveness.
Incorrect. While these attributes are important in data management and usability, they do not directly define cybersecurity controls.
Option D: Authorization, logical access, and physical access.
Incorrect. While these are essential security components, they fall under broader IT security measures rather than forming the fundamental principles of cybersecurity.
NEW QUESTION # 512
An entity sells a durable good to a customer on January 1, Year 1, and the customer is automatically given a 1-year warranty. The customer also buys an extended warranty package extending the coverage for an additional 2 years to the end of Year 3. At the time of the original sale, the company expects warranty costs to be incurred evenly over the life of the warranty contracts. The customer has only one warranty claim durln2 the 3-year period, and the claim occurs during Year 2. The company will recognize income from the sale of the extended warranty:
Answer: D
Explanation:
Because warranty costs are expected to be incurred evenly over the life of the warranty contracts, the income should be recognized on the straight-line basis over the life of the extended warranty contract.
NEW QUESTION # 513
An organization created a formalized plan for a large project. Which of the following should be the first step in the project management plan?
Answer: A
Explanation:
The first step in a project management plan is to break the project into manageable components, known as Work Breakdown Structure (WBS). This step ensures clarity, task allocation, and effective tracking.
* (A) Estimate time required to complete the whole project.
* Incorrect: Time estimation comes after breaking the project into smaller tasks.
* (B) Determine the responses to expected project risks.
* Incorrect: Risk management is important but is planned after defining project tasks and scope.
* (C) Break the project into manageable components. (Correct Answer)
* Dividing the project into smaller tasks (WBS) helps in resource allocation, scheduling, and risk assessment.
* IIA GTAG 12 - Project Risk Management suggests using WBS to define tasks clearly.
* (D) Identify resources needed to complete the project.
* Incorrect: Resources can only be allocated effectively after defining project components.
* IIA GTAG 12 - Project Risk Management: Recommends Work Breakdown Structure (WBS) as the first step in project planning.
* PMBOK (Project Management Body of Knowledge): Defines WBS as the foundation of project planning.
Analysis of Each Option:IIA References Supporting the Answer:Thus, the correct answer is (C) Break the project into manageable components, as this is the first step in structuring and planning a successful project.
NEW QUESTION # 514
A technology developer has entered a two-year contract with another organization to design new software.
According to IIA guidance, which of the following provisions of this agreement would be the most effective to protect the developer ' s product knowledge and expertise?
Answer: C
Explanation:
Intellectual property rights are the most effective contractual provision to protect a technology developer's product knowledge, software design, source code, algorithms, documentation, methods, and expertise. A right- to-audit clause helps verify compliance with contract terms but does not itself define ownership or protection of proprietary work. A performance measurement system evaluates service quality, timeliness, or deliverables. Defined roles and responsibilities clarify accountability, but they do not protect ownership of product knowledge. Internal auditors reviewing technology contracts should verify that intellectual property, confidentiality, licensing, source-code ownership, derivative works, data rights, and post-termination restrictions are clearly addressed. Without strong IP provisions, the developer may lose control over valuable knowledge embedded in the software development process. Therefore, Option D is correct.
NEW QUESTION # 515
IAS 34, interim Financial Reporting, provides guidelines for interim reporting stating that enterprises:
Answer: C
Explanation:
Essentially the same reporting methods should be used for interim and annual financial statements. However, the preparation of interim financial reports ordinarily requires a greater use of estimates. For example. IAS 34 states that complete inventory-taking and valuation may not be required at interim dates. Estimates based on sales margins may suffice. Copper Co. had the pre-closing trial balance at December 31 shown below. Additional information: The balance of opening inventory was US $140,000. The long term debt pays interest at a rate of 10% per annum, payable every 12 months. The debt was issued on July 1 of the current year and originally had 5 years to maturity. The assets classified as property, plant, and equipment have a 10-year estimated useful life and were 1 year old at the start of the current year Straight-line depreciation is used.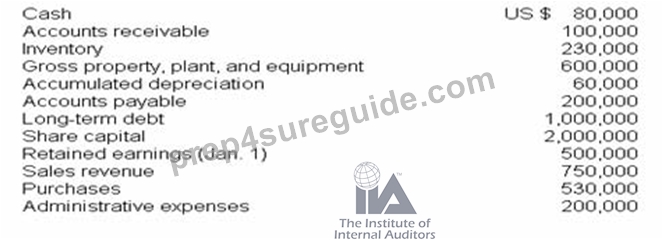
NEW QUESTION # 516
......
To get respected jobs in tech companies around the globe, hundreds of people take the IIA certification exam every year. Once they clear IIA IIA-CIA-Part3 Exam, they easily get jobs and promotions. Hundreds of applicants who appear in the IIA IIA-CIA-Part3 Exam don't get a passing score. The major reason behind their failure in the IIA IIA-CIA-Part3 Exam is studying the material which is not the latest. So, to save your resources, you must prepare with IIA IIA-CIA-Part3 Dumps which has real and updated exam material.
New IIA-CIA-Part3 Test Forum: https://www.prep4sureguide.com/IIA-CIA-Part3-prep4sure-exam-guide.html
2026 Latest Prep4sureGuide IIA-CIA-Part3 PDF Dumps and IIA-CIA-Part3 Exam Engine Free Share: https://drive.google.com/open?id=1c0cPiqfZJUodY1x_PDA-nCvh0A0OcQT-