P.S. Free 2026 Real Estate Massachusetts-Real-Estate-Salesperson dumps are available on Google Drive shared by Prep4sureExam: https://drive.google.com/open?id=10wXv8dmJsYaHwUyz1-wwq8cAXY470W8j
Dear, when you find Real Estate Massachusetts-Real-Estate-Salesperson practice training, please assess it with careful analysis and do not miss it any more. The Massachusetts-Real-Estate-Salesperson free demo is available and accessible for download. You can have a try and do your decision. In addition, it is very easy to make an order with our streamline process. Then you can get the Massachusetts-Real-Estate-Salesperson Test Dumps in about 5-10 mins after payment and instant download it, and start study.100% is the guarantee of us, so please test assured to purchase Massachusetts-Real-Estate-Salesperson practice torrent.
| Section | Weight | Objectives |
|---|---|---|
| National Portion | 67% | - Transfer of Title
|
| Massachusetts State Portion | 33% | - Landlord-Tenant Law
|
>> Massachusetts-Real-Estate-Salesperson Exam Questions <<
The online Massachusetts-Real-Estate-Salesperson practice exam has all specifications of the desktop software. It is compatible with Chrome, Firefox, MS Edge, Safari, Opera, etc. The Massachusetts Real Estate Salesperson Exam (Massachusetts-Real-Estate-Salesperson) practice exam will save your progress and give you an overview of your mistakes, which will benefit your overall preparation. All operating systems support this Massachusetts Real Estate Salesperson Exam (Massachusetts-Real-Estate-Salesperson) practice test.
NEW QUESTION # 316
A ranch house with a double garage is being valued. The house next door, which is similar except that it lacks a garage and has an outside deck, was sold last month for $138,000. Experience in that area shows that a two- car garage is probably worth $10,000 to buyers, while in general, they will pay only $500 extra for a deck.
The ranch house is most likely to sell for around
Answer: A
Explanation: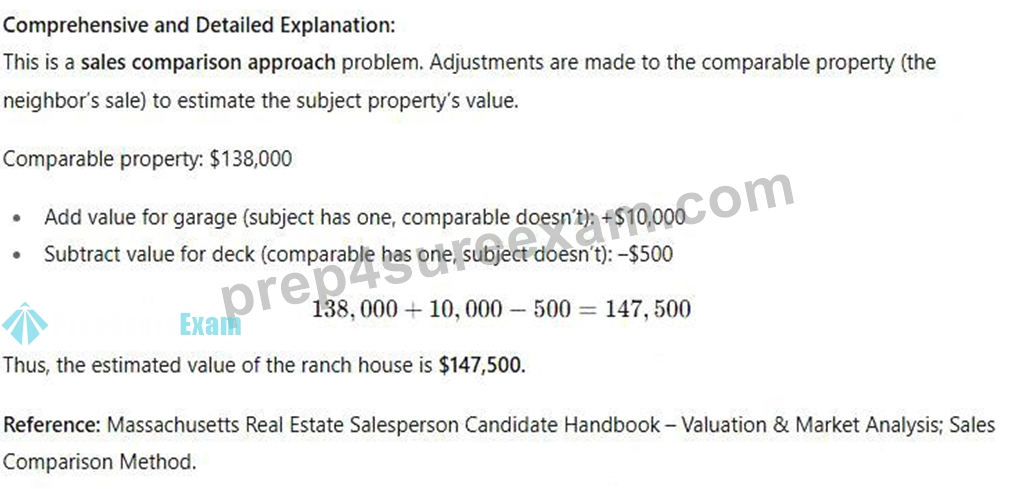
NEW QUESTION # 317
The Massachusetts Sanitary Code requires landlords to
Answer: A
Explanation:
The Massachusetts State Sanitary Code (105 CMR 410) establishes minimum standards for human habitation.
Landlords are required to ensure that rental units are kept in a safe, sanitary, and habitable condition at all times. This includes maintaining heating systems, hot water, structural integrity, pest control, and ensuring compliance with health and safety standards.
While landlords may provide a statement of condition when collecting a security deposit (per M.G.L. c. 186,
15B), this is not part of the Sanitary Code itself. Similarly, no law requires inspections every six months or a
24-hour notice of entry (although reasonable notice is considered best practice and is recommended in case law).
The essential legal requirement is habitability. Tenants have the right to withhold rent or seek remedies if the landlord fails to maintain the property in compliance with the Sanitary Code. Local boards of health enforce these regulations.
Reference: Massachusetts Sanitary Code, 105 CMR 410; M.G.L. c. 186, 14; Massachusetts Real Estate Salesperson Study Guide - Landlord/Tenant Law.
NEW QUESTION # 318
Which process can convert an item that is part of real property into personal property?
Answer: A
Explanation:
Severance is the physical or legal act of removing an item from the real estate so that it becomes personal property. Therefore C is correct. A common example is a tree growing in the ground: while rooted to the land, it is ordinarily part of the real property. Once cut down and separated from the soil, the resulting timber generally becomes personal property.
Annexation describes essentially the reverse process. Personal property can become a fixture-and therefore part of the real estate-when it is attached with sufficient permanence and with circumstances showing an intent that it remain. The precise fixture analysis can involve the method of attachment, adaptation to the property, relationship of the parties, and intention.
Hypothecation concerns pledging property as security while retaining possession; it does not convert realty into personalty. A fiduciary relationship concerns duties of trust and loyalty and has nothing to do with the physical classification of property.
The real-property/personal-property distinction is important in sales contracts because parties should make clear whether movable items are included, excluded, or separately conveyed.
Study Guide Reference: Property Ownership - real versus personal property; fixtures, annexation and severance.
NEW QUESTION # 319
A vacant lot has a market value of $40,000. It is assessed at 40% of market value, and an equalization factor of 1.5 is applied. The tax rate is $4 per $100 of adjusted assessed value. What is the tax?
Answer: B
Explanation:
The correct answer is C, $960.
First calculate the assessed value:
$40,000 × 40% = $16,000
Apply the equalization factor:
$16,000 × 1.5 = $24,000 adjusted assessed value
The tax rate is $4 per $100, which is equivalent to 4%:
$24,000 ÷ 100 = 240 tax units
240 × $4 = $960
Therefore, C is correct.
The examination trap is recognizing that the equalization factor must be applied before calculating the final tax under the assumptions provided.
In actual Massachusetts municipal taxation, assessors determine values and municipalities establish tax rates under Massachusetts property-tax law. Real-world procedures do not necessarily mirror every simplified national exam formula involving equalization factors.
For exam mathematics, however, candidates should apply the figures exactly in the sequence supplied.
Study Guide Reference: Real Estate Calculations - Property Tax Assessments, Equalization and Tax Rates.
NEW QUESTION # 320
A home has an assessed taxable value of $840,000. The local property-tax rate is $15 for every $1,000 of assessed value. What is the quarterly property-tax amount?
Answer: A
Explanation:
The correct answer is A, $3,150.
First convert the assessed value into $1,000 units:
$840,000 ÷ $1,000 = 840 units.
Next multiply by the stated tax rate:
840 × $15 = $12,600 annual property tax.
Because the question requests the quarterly amount, divide the annual tax by four:
$12,600 ÷ 4 = $3,150.
Therefore, A is correct.
The principal examination issue is recognizing how a tax rate expressed "per $1,000" is applied. Candidates should not multiply $840,000 directly by 15%. The $15 figure is not a percentage; it represents $15 of tax for every $1,000 of taxable assessed value.
Massachusetts municipalities establish property-tax rates based on assessed valuation and applicable classifications. Actual assessments, exemptions, abatements, and municipal rates vary, but examination calculations generally give all information required.
Study Guide Reference: Real Estate Calculations - property taxes, assessed value, tax rates and periodic payments.
NEW QUESTION # 321
......
Exam Massachusetts-Real-Estate-Salesperson tests your professional talent and expertise. This is the reason that passing this Massachusetts Real Estate certification exam has been a tough challenge for professionals. But it is made easy now to ace it! The recently developed Prep4sureExam's Massachusetts-Real-Estate-Salesperson Exam Questions dumps aim at to deliver you the shortest possible route to obtaining Massachusetts-Real-Estate-Salesperson without any chance of losing the exam.
Massachusetts-Real-Estate-Salesperson Instant Discount: https://www.prep4sureexam.com/Massachusetts-Real-Estate-Salesperson-dumps-torrent.html
P.S. Free & New Massachusetts-Real-Estate-Salesperson dumps are available on Google Drive shared by Prep4sureExam: https://drive.google.com/open?id=10wXv8dmJsYaHwUyz1-wwq8cAXY470W8j