Laden Sie die neuesten ZertFragen PF1 PDF-Versionen von Prüfungsfragen kostenlos von Google Drive herunter: https://drive.google.com/open?id=1XGifBF9kI9XJzyOkp_-5h9Pkuy4piB-F
Wollen Sie an National Payroll Institute PF1 Zertifizierungsprüfung teilnehmen? Sorgen Sie sich um diese Prüfung? Wünschen Sie sich an der PF1 Prüfung melden aber Fürchten Sie Misserfolg an dieser Prüfung? Das macht nichts, melden Sie getrost an. Wenn Sie ZertFragen Prüfungsunterlagen benutzen, sind keine Probleme in Ihrer Prüfung vorhanden. Obwohl Sie keine Zuversicht dieser Prüfung haben, können Sie einmal diese Prüfung bestehen, wenn Sie PF1 Dumps von ZertFragen benutzen. Glauben Sie nicht? Kommen Sie bitte zu ZertFragen und Informieren Sie sich. Außerdem können Sie einen Teil der National Payroll Institute PF1 Dumps probieren. Damit können Sie finden, dass die Prüfungsunterlagen die Garantie für den Erfolg der National Payroll Institute PF1 Prüfung sind.
| Section | Objectives |
|---|---|
| Topic 1: Earnings, Deductions, and Taxation | - Deductions and remittances
|
| Topic 2: Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Topic 3: Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
Hier Zeigen wir Ihnen den Grundwert von ZertFragen. ZertFragen Dumps haben die Durchlaufrate mit 100%. ZertFragen Dumps sind die Zusammenfassung von den reichen Erfahrungen der IT-Eliten und wertsvoll. Sie können Dumps benutzen, um National Payroll Institute PF1 Zertifizierungsprüfungen vorzubereiten und auch Ihre Fähigkeiten zu entwickeln. Außerdem wenn Sie andere Prüfungskenntnisse kennen lernen, kann es Ihren Wunsch erfüllen.
39. Frage
By the authority of which Act can the Canada Revenue Agency garnish the wages of an employee who has failed to pay Employment Insurance premiums, Canada Pension Plan contributions, or income tax deductions?
Antwort: C
Begründung:
The CRA's wage garnishment tool is commonly issued as a Requirement to Pay (RTP) (and related instruments such as ERTP/DTP), which directs a third party (often the employer) to redirect amounts that would otherwise be paid to the employee, and send them to the government instead. CRA guidance explains that when an employee owes money, the CRA can send the employer a requirement to pay notice, and the employer must remit the amounts as instructed (or the employer can become liable).
The legal authority for the CRA to issue a Requirement to Pay is found in the Income Tax Act, including section 224, which sets out the mechanism and consequences for non-compliance.
In payroll operations, this is a communication-and-compliance issue: payroll must correctly interpret the notice, apply the withholding/remittance as directed, and communicate impacts to internal stakeholders (HR
/finance) and, where appropriate, the affected employee-while ensuring the remittance is made exactly as the CRA notice requires.
40. Frage
Which statutory deductions is salary continuance subject to?
Antwort: C
Begründung:
Salary continuance means the employee continues to receive regular pay (and often benefits) for a period after their job ends. In this arrangement, the payments are treated like regular employment income for payroll purposes, so the usual payroll deductions apply. A Government of Canada guidance page explains that when severance is paid as salary continuance, the employee pays income tax like regular employment income and that the usual deductions apply, including CPP (or QPP), EI premiums, and RPP contributions (where applicable).
This aligns with standard payroll obligations in CRA's payroll remittance framework: employers deduct and remit CPP contributions, EI premiums, and income tax on employment income unless a specific exemption applies.
Therefore, the correct option is B (All deductions)-and in Quebec, that "all deductions" concept includes Quebec-specific programs (for example QPP/QPIP where applicable) based on the employee's province of employment and insurability rules.
41. Frage
The source deductions form completed by all new employees in Quebec is called:
Antwort: A
Begründung:
In Quebec, employees must complete a Quebec-specific source deductions form so the employer can calculate Quebec income tax to withhold. Revenu Quebec identifies Form TP-1015.3-V (Source Deductions Return) as the form employees complete and provide to their employer/payer for this purpose. It is part of the onboarding
/payroll setup process in Quebec and is used to determine personal tax credits and any additional withholding instructions for Quebec provincial income tax.
The other options are not the standard Quebec source deductions return for new employees: T1213 is a CRA form used to request a reduction in tax deductions at source (federal), TD1-AB is a provincial TD1 for Alberta (not Quebec), and T2222 is not the Quebec source deductions return. From a payroll communication standpoint, the employer should request both the applicable federal TD1 and the Quebec TP-1015.3-V, then retain them on file to support accurate withholding calculations.
42. Frage
Dollar values attributed to something the employer has either provided to an employee or paid for on an employee's behalf are:
Antwort: B
Begründung:
The CRA defines a benefit as something the employee receives when the employer pays for or gives something that is personal in nature (a good or service), either directly to the employee or through a third party. CRA's T4130 guide describes a benefit as a good or service you give (or arrange for) such as free use of employer property, and it is the value of that benefit that may need to be included in the employee's income if taxable.
This matches the wording in the question: "dollar values attributed to something the employer has either provided...or paid for...on an employee's behalf." By contrast, earnings are pay for work performed (salary, wages, commissions). Allowances are fixed amounts paid to help cover anticipated expenses without receipts (often taxable unless an exception applies). Expense reimbursements repay actual business expenses (typically supported by receipts) and are generally not treated as earnings.
So the correct classification is Benefits.
43. Frage
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
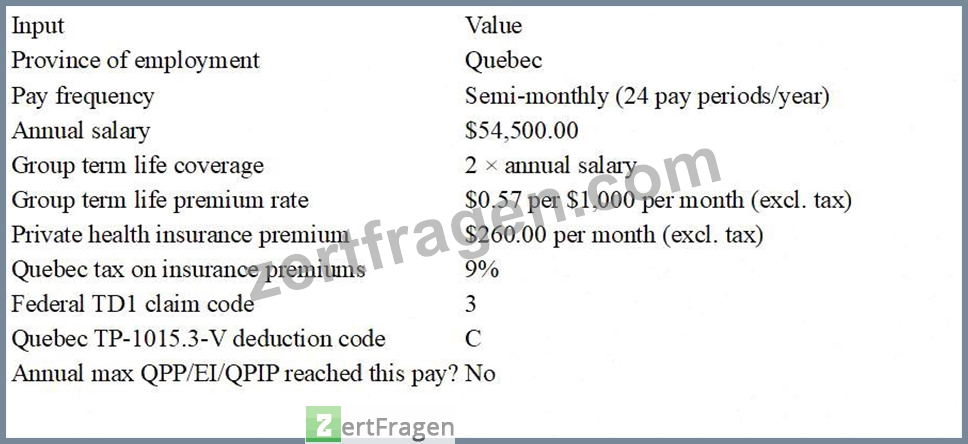
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases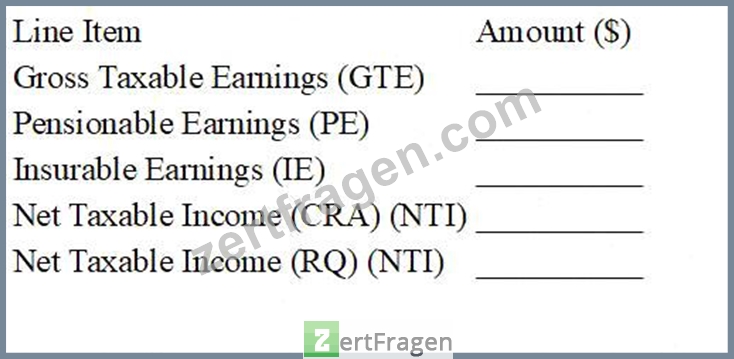
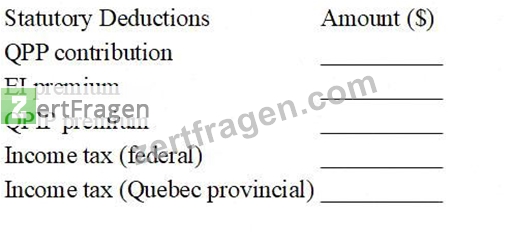
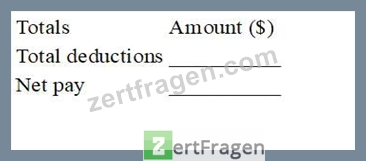
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Antwort:
Begründung:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
44. Frage
......
ZertFragen ist eine Website voller Zuversicht. Die IT-Profis von ZertFragen widmen sich der Studie der vielfältigen IT-Zertifizierungsprüfungen, um die Effektivität der Erfolg der National Payroll Institute PF1 Zertifizierungsprüfungen zu verbessern. Solange Sie einmal ZertFragen Unterlagen probieren, wollen Sie unbedingt sie wieder benutzen, weil wir ZertFragen nicht nur Ihnen die besten National Payroll Institute PF1 Zertifizierungsunterlagen, sondern auch den besten Service anbieten. Wenn Sie irgendwelche Meinungen haben, senden Sie bitte ihre Vorschläge an uns per E-Mail. Wir hoffen, wir helfen Kadidaten Erfolg machen und auch bieten den besten Service.
PF1 Fragen Antworten: https://www.zertfragen.com/PF1_prufung.html
2026 Die neuesten ZertFragen PF1 PDF-Versionen Prüfungsfragen und PF1 Fragen und Antworten sind kostenlos verfügbar: https://drive.google.com/open?id=1XGifBF9kI9XJzyOkp_-5h9Pkuy4piB-F