BTW, DOWNLOAD part of ActualTorrent PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1HblpJ6gPYdOxZH3Jjgx0wq0N2NbHA0JL
If you want to pass your exam and get your certification, we can make sure that our PF1 guide questions will be your ideal choice. Our company will provide you with professional team, high quality service and reasonable price. In order to help customers solve problems, our company always insist on putting them first and providing valued service. We are living in the highly competitive world now. We have no choice but improve our soft power, such as get PF1 Certification. It is of great significance to have PF1 guide torrents to pass exams as well as highlight your resume, thus helping you achieve success in your workplace.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Termination and Special Payments | 30% | - Leaves and absences
|
| Topic 2: Individual Pay Calculations | 40% | - Non-regular earnings
|
| Topic 3: Record of Employment (ROE) | 20% | - Submission and deadlines
|
| Topic 4: Communication and Compliance | 10% | - Stakeholder communication
|
>> National Payroll Institute PF1 Latest Braindumps Sheet <<
If candidates want to obtain certifications candidates should notice studying methods. If you do not want to purchase our National Payroll Institute PF1 new exam bootcamp materials and just want to study yourself, willpower is the most important. Passing so many exams is really not easy. Reasonable studying methods and relative work experience make you half the work with double the results. PF1 New Exam Bootcamp materials will be a shortcut for you.
NEW QUESTION # 52
What is the portion of a retiring allowance eligible to be transferred into a Registered Retirement Savings Plan (RRSP) or a registered pension plan (RPP) tax free based on?
Answer: A
Explanation:
The CRA sets out that the "eligible" portion of a retiring allowance that may be transferred directly to an RRSP/RPP under special rules is based on years of service before 1996 (and potentially an additional amount for certain pre-1989 years if specific pension/DPSP conditions are met). The CRA explains the eligible part is
$2,000 for each year (or part-year) of service before 1996, plus you may be able to transfer an additional
$1,500 for each year (or part-year) of service before 1989 where no employer pension/DPSP benefit was vested (or previously paid) for those years.
This is why the correct basis in the answer choices is the employee's years of service prior to 1996, not wages, age, or average earnings. Payroll needs this service history (including related employers where applicable) to correctly identify the eligible/non-eligible split and apply the right withholding and transfer reporting.
NEW QUESTION # 53
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
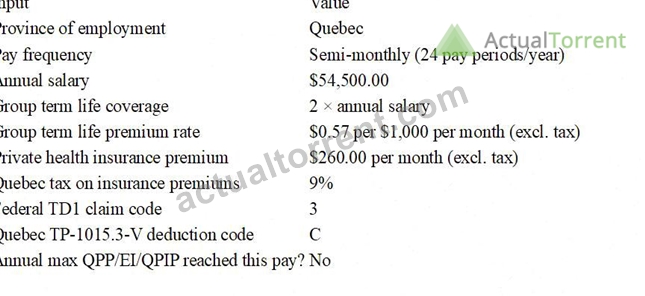
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases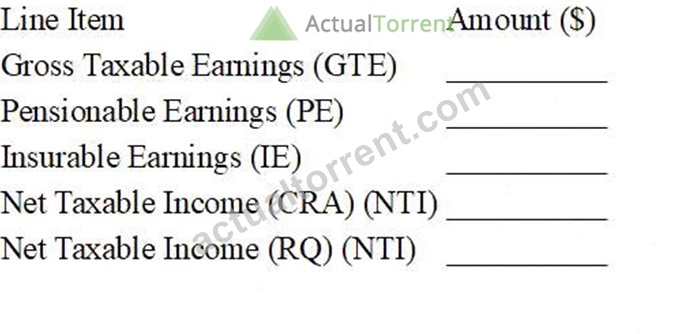
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
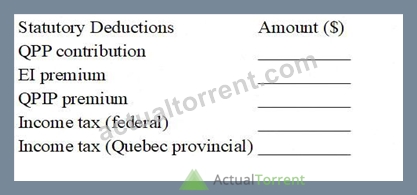
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
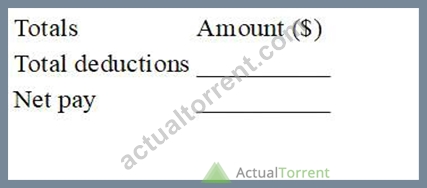
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 54
Matt earns $10.10 per hour and works 37.5 hours per week. Calculate Matt's regular bi-weekly earnings.
Answer:
Explanation:
$757.50
Explanation:
Regular earnings for an hourly employee are calculated as hourly rate × hours worked. Because "bi-weekly" means two weeks of work paid together, you calculate one week's regular earnings and then multiply by two (assuming the hours are the same each week and there is no overtime premium indicated).
Step 1: Weekly regular earnings:
$10.10 × 37.5 hours = $10.10 × 37 + $10.10 × 0.5
= $373.70 + $5.05
= $378.75.
Step 2: Bi-weekly regular earnings (2 weeks):
$378.75 × 2 = $757.50.
So Matt's regular bi-weekly earnings are $757.50.
In payroll documentation, "regular earnings" are the employee's base wages before statutory deductions (CPP
/QPP, EI, income tax) and before other deductions, and they exclude any separately calculated earnings like overtime premiums or taxable benefits unless stated. This approach (rate × hours, then adjust for pay period) is the standard method used to compute gross/regular pay for hourly employees before moving on to deductions and net pay.
NEW QUESTION # 55
The formula for calculating net pay is:
Answer: D
Explanation:
Net pay (often called "take-home pay") is what the employee actually receives after all withholdings and other deductions are taken from their earnings. In Canadian payroll practice, the starting point is gross earnings (regular wages plus any taxable amounts that must be included in income). From gross earnings, payroll subtracts total deductions, which include statutory deductions (such as CPP/QPP, EI, and income tax) and any authorized non-statutory deductions (for example, union dues, benefits premiums, pension contributions, or garnishments where applicable). This is why the most accurate generic formula is gross earnings # total deductions. CRA payroll guidance reflects this structure by requiring employers to calculate gross pay, determine the correct statutory deductions, and then arrive at the amount paid to the employee after those deductions are withheld and remitted.
Options C and D are incomplete or incorrect because "total tax" is only one part of deductions, and "net taxable income" is not a payroll calculation base in the way the question frames it. Option A is also incorrect because "pensionable earnings" is only relevant to CPP/QPP calculations, not the overall net pay formula.
NEW QUESTION # 56
Alyssa is a member of her employer's Defined Contribution Pension Plan. The plan defines the contribution as 3% of the employee's pensionable earnings, with the employer matching the employee's contribution.
Alyssa's pensionable earnings are $3,400.00 per month. Calculate the total payment to be remitted to Alyssa's Defined Contribution Pension Plan each month.
Answer:
Explanation:
$204.00 per month
Explanation:
In a Defined Contribution (DC) pension plan, contributions are calculated as a set percentage of the employee' s pensionable earnings, and the total remittance is usually the sum of the employee deduction plus the employer's matching contribution, based on the plan text. Here, the plan states the employee contributes 3% of pensionable earnings, and the employer matches the employee contribution.
Step 1: Calculate the employee's pension contribution:
3% × $3,400.00 = 0.03 × 3,400.00 = $102.00.
Step 2: Calculate the employer match:
Because the employer matches the employee contribution, the employer contributes $102.00 as well.
Step 3: Total remittance to the plan:
$102.00 (employee) + $102.00 (employer) = $204.00 each month.
From a payroll processing perspective, the employee amount is withheld from gross pay as a payroll deduction according to plan rules, while the employer match is recorded as an employer expense. Payroll remits both amounts to the plan administrator following the plan's remittance schedule, and should reconcile pensionable earnings and contributions to ensure accuracy and compliance with plan terms.
NEW QUESTION # 57
......
A National Payroll Institute PF1 practice questions is a helpful, proven strategy to crack the National Payroll Institute PF1 exam successfully. It helps candidates to know their weaknesses and overall performance. ActualTorrent software has hundreds of National Payroll Institute exam dumps that are useful to practice in real time. The Payroll Fundamentals 1Exam (PF1) practice questions have a close resemblance with the actual PF1 exam.
PF1 Detailed Study Plan: https://www.actualtorrent.com/PF1-questions-answers.html
BTW, DOWNLOAD part of ActualTorrent PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1HblpJ6gPYdOxZH3Jjgx0wq0N2NbHA0JL