P.S. Kostenlose und neue L4M7 Prüfungsfragen sind auf Google Drive freigegeben von Fast2test verfügbar: https://drive.google.com/open?id=1Ta4or-oAsf_xqYUgSouBNNTLoKnPi7jw
Warum sind wir vorrangiger als die anderen Websites? Weil die CIPS L4M7 Schulungsunterlagen von uns die umfassendste, die genaueste sind. Außerdem sind sie von guter Qualität. So ist Fast2test Ihnen die beste Wahl und die beste Garantie zur CIPS L4M7 Zertifizierungsprüfung.
Die CIPS L4M7 -Prüfung ist in drei Einheiten unterteilt, von denen jedes auf den in der vorherigen Einheit entwickelten Wissen und Fähigkeiten aufbauen soll. Die erste Einheit deckt die Prinzipien des Vermögensmanagements und die Bedeutung der Kosten für das Gesamtleben ab. Die zweite Einheit konzentriert sich auf die Beschaffung von Vermögenswerten, einschließlich der Auswahl der Lieferanten, der Vertragsmanagement und der Verwendung von Beschaffungswerkzeugen und -techniken. Die dritte Einheit deckt den Betrieb und die Wartung von Vermögenswerten ab, einschließlich Leistungsmanagement, Risikomanagement und der Verwendung von Technologie im Vermögensverwaltung.
Wenn Sie Ihre Stelle in der schärf konkurrierten IT-Branche durch das Zertifikat von CIPS L4M7 festigen und somit Ihre beruflichen Fähigkeiten verstärken wollen, können Sie die Schulungsunterlagen zur CIPS L4M7 Zertifizierungsprüfung von unserem Fast2test wählen. Nach langjährigen Bemühungen haben unsere Erfolgsquote von der CIPS L4M7 Zertifizierungsprüfung 100% erreicht. Wählen Sie Fast2test, wählen Sie Erfolg.
Die CIPS L4M7 -Zertifizierungsprüfung ist eine umfassende Prüfung, die eine breite Palette von Themen im Zusammenhang mit dem Vermögensverwaltung abdeckt, einschließlich der Planung, Übernahme, Wartung, Entsorgung und Leistungsmanagement von Vermögenswerten. Die Prüfung wurde entwickelt, um die Fähigkeiten und Kenntnisse zu testen, die erforderlich sind, um die Vermögenswerte während ihres gesamten Lebenszyklus effektiv zu verwalten.
124. Frage
When accounting for the disposal of fixed assets, the gain or loss on disposal is equal to...?
Antwort: C
Begründung:
Fixed assets may be sold anytime during their useful life. This gives rise to the need to derecognize the asset from balance sheet and recognize any resulting gain or loss in the income statement.
The accounting for disposal of fixed assets can be summarized as follows:
- Record cash receive or the receivable created from the sale:
Debit Cash/Receivable
- Remove the asset from the balance sheet
Credit Fixed Asset (Net Book Value)
- Recognize the resulting gain or loss
Debit/Credit Gain or Loss (Income Statement)
Example
ABC LTD purchased a machine for $2000 on 1st January 2001 which had a useful life of 5 years and an estimated residual value of $500. The machine was being depreciated on straight line basis. However, ABC LTD decided to sell the asset on1 January 2003 for $1500 in order to raise cash for the purchase of a new machine.
The disposal of the fixed asset will be recorded as follows:
Record cash received or the receivable arising from the sale:
Debit Cash $1,500
Remove the asset from the balance sheet
As a fixed asset is recognized in the balance sheet at the Net Book Value (i.e. Cost less Accumulated Depreciation), the machine will be removed from the accounts of ABC LTD in two parts:
First, the Machine Cost must be removed by crediting the ledger:
Credit Machine Cost $2,500
Second, the Accumulated Depreciation in respect of the machine must be removed by debiting the ledger:
Debit Accumalated Depreciation $600*
*Accumulated Depreciation: (2000 - 500)/5 x 2 Years
The combined effect of the above two transactions would be to remove the machine's net book value of $1400 (2000 - 600) from the balance sheet.
Recognize the resulting gain or loss on the sale of machine
ABC LTD received $1500 for an asset with a balance sheet worth of $1400. It therefore earned a gain of $100. The gain will be recorded as follows:
Credit Gain on Disposal $100
Reference:
- Accounting for Disposals
- CIPS study guide page 197-198
LO 3, AC 3.3
125. Frage
In a manufacturing facility, which types of inventory have the lowest value?
1. Finished goods
2. Secondary components
3. Work in progress
4. Raw materials
Antwort: A
Begründung:
Raw materials are basic input materials - they are only processed limitedly or have not been pro-cessed at all.
Their values are equal to acquisition cost and are the lowest value of stock held.
Secondary components are the products that are combined with others to produce the finished goods. They are acquired in the processed state. Their value is higher than raw materials, but still at acquisition cost.
Work in progress is the stock part-way through manufacture that has not been finished. It is typically not completed yet, so it doesn't have full value. But the costs of processing already carried out makes it more valuable than materials and components.
Finished goods are completed and ready to be used or sold. Finished goods are the most expensive and need to be stored in good conditions.
126. Frage
What are the contents of master production schedule in MRP system?
Antwort: A
Begründung:
A master production schedule (MPS) is a plan for individual commodities to be produced in each time period such as production, staffing, inventory, etc.[1] It is usually linked to manufacturing where the plan indicates when and how much of each product will be demanded.[2] This plan quantifies significant processes, parts, and other resources in order to optimize production, to identify bottlenecks, and to anticipate needs and completed goods. Since a MPS drives much factory activity, its accuracy and viability dramatically affect profitability. Typical MPSs are created by software with user tweaking.
Reference:
LO 2, AC 2.3
127. Frage
The only reason stocks become obsolete is because items have been held in stock for a very long time. Is this a valid statement?
Antwort: C
128. Frage
Which of the following are the different types of inventory that a manufacturing company usually has?
1. Work in progress
2. Economic order quantity
3. Raw materials
4. Finished goods
Antwort: D
Begründung:
The normal breakdown in a manufacturing organisation would be raw materials, components, work in progress and finished goods.
Following are the different types of inventory: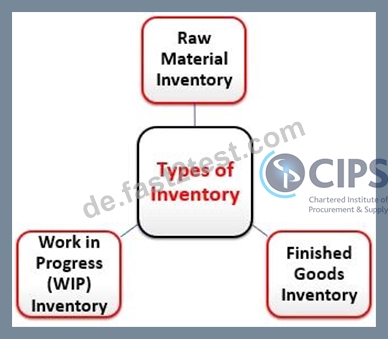
Raw materials are the basic materials that a manufacturing company buys from its suppliers, and that is used by the former to convert them into the final products by applying a set of manufacturing processes. For example, aluminum scrap is the raw material for a company that produces aluminum ingots. Flour is the raw material for a company that produces bread or pizza. Similarly, metal parts and ingots are the raw materials bought by a company that manufactures cars, and crude oil is the raw material for an oil refinery.
Work in progress inventory can also be called semi-finished goods. They are the raw materials that have been taken out of the raw materials store and are now undergoing the process of their conversion into the final products. These are the partly processed raw materials lying on the production floor. And they have also not reached the stage where they have been converted into the final product.
Finished goods are indeed the final products obtained after the application of the manufacturing processes on the raw materials and the semi-finished goods discussed above in the article. They are saleable, and their sale contributes fully to the revenue from the core operations of the company.
Reference:
- Types of Inventory
- CIPS study guide page 82-83
LO 2, AC 2.1
129. Frage
......
L4M7 Deutsche: https://de.fast2test.com/L4M7-premium-file.html
P.S. Kostenlose 2026 CIPS L4M7 Prüfungsfragen sind auf Google Drive freigegeben von Fast2test verfügbar: https://drive.google.com/open?id=1Ta4or-oAsf_xqYUgSouBNNTLoKnPi7jw