P.S. JPNTestがGoogle Driveで共有している無料かつ新しいLLQPダンプ:https://drive.google.com/open?id=1P5UKTgl0OH4WHYLQi4u6AJ16_Icev0B1
すべてのお客様に24時間のオンラインアフターサービスを提供します。 LLQPの実際の試験のインストールまたは使用について質問がある場合は、専門のアフターサービススタッフがウォームリモートサービスを提供します。 LLQP学習教材に関する限り、解決することができます。メールでお問い合わせいただく場合でも、オンラインでお問い合わせいただく場合でも、できるだけ早く問題を解決できるようサポートいたします。心配する必要はまったくありません。LLQPトレーニングの質問のインストールまたは使用を懸念しているお客様がいるかもしれません。これについて心配する必要はありません。
| Section | Objectives |
|---|---|
| Ethics and Professional Practice | - Ethical conduct and suitability - Regulatory framework and compliance |
| Segregated Funds and Annuities | - Investment-linked insurance products - Annuity structures and guarantees |
| Accident and Sickness Insurance | - Disability and critical illness coverage - Health insurance principles |
| Life Insurance | - Life insurance products and policy types - Policy provisions and riders - Underwriting and risk classification |
IFSE Institute人々は最近非常に忙しいので、LLQP試験の準備に昼食時間を有効に活用したいと考えています。 学習ツールとしてLLQP試験問題を選択した場合、問題は解決しません。 LLQP試験準備のアプリはいつでもオフラインでの練習をサポートしているためです。 当社の製品を購入する場合、JPNTestオフライン状態でも学習を続けることができます。 Life License Qualification Program (LLQP)ネットワーク全体の不可能な状態に影響されることはありません。 いつでもどこでも当社のLLQP試験準備を使用することを選択できます
質問 # 243
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
正解:D
解説:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
* Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence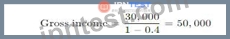
Calculate Required Capital for Income Replacement:Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence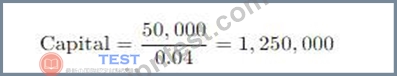
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
質問 # 244
Concilius has had a whole life (permanent) insurance policy for the past eight years. He decides he no longer wants this policy and stops paying the premiums. The cash value keeps the policy in effect for 28 months, after which it lapses. However, 46 months later, Concilius regrets his decision and applies to reinstate his policy. He is prepared to prove that he still meets the insurability conditions and to pay the overdue premiums plus interest, the cash value used, and the interest. Under what conditions will Concilius' policy be reinstated?
正解:A
解説:
Comprehensive and Detailed In-Depth Explanation: Reinstatement of a lapsed whole life insurance policy is governed by the Civil Code of Quebec (Article 2428) and insurer policies outlined in the LLQP. If a policy lapses due to non-payment but has a cash value, it may remain in force temporarily via an automatic premium loan or reduced paid-up option. For reinstatement, the insured typically must provide evidence of insurability and repay overdue premiums, interest, and any cash value used, as Concilius offers. The LLQP specifies that reinstatement, if within the insurer's allowable period (often 2-5 years), restores the policy to its original terms-same premium and coverage-unless otherwise stipulated. Option B, "with the same initial conditions," aligns with this standard practice. Option A (new premium based on age) applies to new policies, not reinstatement. Option C (premium increase) or D (reduced amount) might occur if insurability declines, but Concilius meets the conditions, so no adjustment is required. The Ethics manual stresses transparency in explaining reinstatement terms.
References: Civil Code of Quebec, Article 2428; LLQP Module on Life Insurance Products; Ethics and Professional Practice (Civil Law) Manual, Section on Policy Administration.
質問 # 245
Marsha and Alexis are equal partners in an advertising firm. They meet with Jose, an insurance agent, and Horacio, their lawyer, because they would like to protect themselves if one of them becomes disabled and unable to work for an extended period of time. At the end of their meeting, they agree to purchase $500,000 disability insurance policies on each other by each of them paying premiums.
What type of agreement do Marsha and Alexis have?
正解:A
解説:
In across-purchase agreement, business partners purchase disability or life insurance policies on each other. If one partner becomes disabled, the other partner uses the proceeds from the insurance to buy out the disabled partner's share in the business. Marsha and Alexis have agreed to purchase disability insurance policies on each other, with each paying the premium on the policy for their partner. This structure aligns with the cross- purchase format, where each partner independently holds the policy on the other, as described in LLQP materials on business continuation planning. The other options, such as an entity purchase agreement, involve the business purchasing the policy, which is not the case here.
質問 # 246
(Business owner Timothy is reviewing information that his life insurance agent provided for him to establish a group savings plan for his employees. Timothy then meets the agent for some advice. He wants to avoid having to deal with pension credit adjustments.
Which of the following types of plans would meet this requirement?)
正解:C
解説:
Timothy wants toavoid pension adjustments, which occur with formal pension plans.Group RRSPsand Group TFSAsare not pension plans, so they do not generate a pension credit (adjustment), unlike DPSPs or DCPPs.
Exact Extract:
"GRRSPs and TFSAs are not registered pension plans and thus do not result in pension adjustments against the employee's RRSP contribution room." (Reference:Segfunds-E313-2020-12-7ED, Chapter 1.3.11 Group Plans#49:3†Segfunds-E313-2020-12-7ED.
pdf**)
質問 # 247
(Jack is starting a new job with group medical, dental, and retirement benefits. He submits his application but is told he is not immediately eligible.
When might Jack become eligible?)
正解:A
解説:
Most group benefits, including medical, dental, and retirement plans, require employees to complete a standard waiting period(e.g., 3 months) before they become eligible for enrollment.
Exact Extract:
"Group insurance plans often impose a standard waiting period before new employees become eligible for coverage." (Reference:Sickness-E312-2020-12-7ED, Chapter 2.3.3.1 Qualification Period#45:3†Sickness-E312-2020-12-
7ED.pdf**)
質問 # 248
......
IFSE Institute高効率のLLQP学習教材を使用すれば、プロの認定試験に合格した製品を使用しなかった場合に必要な時間の半分を費やすだけで済みます。 このようにして、旅行、パーティー、さらに別の試験の準備をする時間が増えます。 あなたにとってLLQPトレーニングトレント:JPNTestのLife License Qualification Program (LLQP)の利点は、金銭による評価からはほど遠いものです。 一流の専門家チーム、Life License Qualification Program (LLQP)高度な学習コンセプト、完全な学習モデルがあります。 私たちの学習教材であなたのために節約された時間はLLQP、私たちにとって最大のリターンです。
LLQP受験資料更新版: https://www.jpntest.com/shiken/LLQP-mondaishu
P.S. JPNTestがGoogle Driveで共有している無料かつ新しいLLQPダンプ:https://drive.google.com/open?id=1P5UKTgl0OH4WHYLQi4u6AJ16_Icev0B1