P.S. Free & New IIA-CIA-Part2 dumps are available on Google Drive shared by Real4exams: https://drive.google.com/open?id=1JEYgciRrJxO_dRGbIyYf9EBGcmBr4GTQ
Aspiring IIA professionals strive to excel in IIA IIA-CIA-Part2 exams such as the Internal Audit Engagement (IIA-CIA-Part2) to achieve their dream careers. However, passing the IIA-CIA-Part2 Exam can be challenging, especially with a demanding schedule that leaves little time for preparation.
| Section | Weight | Objectives |
|---|---|---|
| Performing the Engagement | 40% | - Development of engagement findings: criteria, condition, cause, and effect - Applying analytical approaches and process mapping techniques - Drawing conclusions and formulating recommendations - Root cause analysis and evaluation of evidence - Evaluation of fraud risk and fraud-related indicators during engagements - Assessing the adequacy and effectiveness of risk management and controls - Assessing compliance with laws, regulations, and organizational policies - Use of technology tools to support engagement execution (e.g., CAATs, data analytics) - Information gathering: interviews, observation, document review, and data analysis - Assessing IT governance, security, and control frameworks |
| Managing the Internal Audit Activity | 20% | - Knowledge management and information sharing across the internal audit activity - Risk-based audit planning and alignment with organizational strategy - Strategic role of internal audit within governance, risk management, and control - Coordination with external auditors and other internal assurance providers - Internal audit operations: planning, organizing, directing, and monitoring - Managing financial, human, and IT resources within the internal audit function |
| Communicating Engagement Results and Monitoring Progress | 20% | - Disseminating final results to appropriate stakeholders - Developing recommendations vs. requesting management action plans vs. collaborative approaches - Communication of engagement results: objectives, scope, conclusions, recommendations, action plans - Management response and action plan tracking - Reporting on the adequacy of management's corrective actions - Attributes of effective engagement communication: accurate, objective, clear, concise, constructive, complete, timely - Monitoring and follow-up on the resolution of engagement findings |
| Planning the Engagement | 20% | - Detailed engagement work program development - Engagement planning procedures including data analytics and sampling - Engagement objectives, scope, and resource allocation - Risk and control identification and assessment for the engagement - Coordination with stakeholders during engagement planning - Understanding business processes, IT systems, and relevant regulations |
>> Test IIA-CIA-Part2 Guide <<
If you are going to purchase IIA-CIA-Part2 Study Materials online, you may pay attention to your money safety. With applying the international recognition third party for the payment, your money and account safety can be guaranteed if you choose us. And the third party will protect your interests. In addition, IIA-CIA-Part2 training materials are high-quality, for we have a professional team to research the latest information, and you can use them at ease. Besides if you have little time to prepare for your exam, you can also choose us, you just need to spend 48 to 72 hours on studying, you can pass the exam. Choose us, and you will never regret!
NEW QUESTION # 255
An internal auditor is assessing the organization's risk management framework. Which of the following formulas should he use to calculate the residual risk?
A)
B)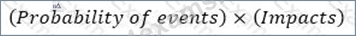
C)
D)
Answer: A
Explanation:
The appropriate formula to calculate residual risk is (Probability of events) × (Impacts). Residual risk is the risk that remains after controls are implemented to mitigate the inherent risk. It reflects the remaining exposure after considering the effectiveness of existing controls. This formula takes into account the likelihood of an event occurring and the potential impact if it does occur. References: IIA Practice Guide - Assessing the Adequacy of Risk Management Processes, COSO Framework
NEW QUESTION # 256
Which of the following reasonably represents best practices regarding what should be the level of internal audit resource investment in monitoring and following up on engagement outcomes?
Answer: B
Explanation:
Best practices in internal auditing emphasize the importance of follow-up on engagement outcomes to ensure that agreed-upon actions are implemented and effective. According to Standard 2500 - Monitoring Progress, the chief audit executive must establish and maintain a system to monitor the disposition of results communicated to management. This ensures that corrective actions are taken and that the internal audit function fulfills its role in improving the organization's governance, risk management, and control processes.
Allocating resources for follow-up is crucial to maintain accountability and support continuous improvement.
References:
* Institute of Internal Auditors (IIA), International Standards for the Professional Practice of Internal Auditing (Standards), Standard 2500 - Monitoring Progress.
NEW QUESTION # 257
A performance audit engagement typically involves:
Answer: C
NEW QUESTION # 258
Which of the following manual audit approaches describes testing the validity of a document by following it backward to a previously prepared record?
Answer: C
Explanation:
Vouching is the manual audit approach that involves testing the validity of a document by following it backward to a previously prepared record. This method helps auditors verify the authenticity and accuracy of transactions by tracing them back to their source documents, such as invoices, receipts, or purchase orders. Vouching is commonly used to detect errors or fraud.
Reference:
The Institute of Internal Auditors (IIA) Standards
Auditing Techniques and Procedures
NEW QUESTION # 259
An internal auditor provided the following statement about division A's performance during the month: "Because supplies of raw material X were scarce, division A's profits declined by 15 percent." Which of the following can be validly concluded from the auditor's statement?
1. Division A's production level declined by 15 percent.
2. Division A could have sold more products than it produced.
3. Division A usually sells all of the products that it produces.
Answer: A
NEW QUESTION # 260
......
It is known to us that the privacy is very significant for every one and all companies should protect the clients’ privacy. Our company has the highly authoritative and experienced team. In order to let customers enjoy the best service, all IIA-CIA-Part2 exam prep of our company were designed by hundreds of experienced experts. Our IIA-CIA-Part2 Test Questions will help customers learn the important knowledge about exam. If you buy our products, it will be very easy for you to have the mastery of a core set of knowledge in the shortest time, at the same time, our IIA-CIA-Part2 test torrent can help you avoid falling into rote learning habits.
IIA-CIA-Part2 Reliable Test Syllabus: https://www.real4exams.com/IIA-CIA-Part2_braindumps.html
2026 Latest Real4exams IIA-CIA-Part2 PDF Dumps and IIA-CIA-Part2 Exam Engine Free Share: https://drive.google.com/open?id=1JEYgciRrJxO_dRGbIyYf9EBGcmBr4GTQ