2026 Latest ActualTorrent PF1 PDF Dumps and PF1 Exam Engine Free Share: https://drive.google.com/open?id=1HblpJ6gPYdOxZH3Jjgx0wq0N2NbHA0JL
ActualTorrent also offers National Payroll Institute PF1 desktop practice exam software which is accessible without any internet connection after the verification of the required license. This software is very beneficial for all those applicants who want to prepare in a scenario which is similar to the Payroll Fundamentals 1Exam real examination.
| Section | Weight | Objectives |
|---|---|---|
| Communication and Compliance | 10% | - Stakeholder communication
|
| Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Individual Pay Calculations | 40% | - Regular earnings
|
| Termination and Special Payments | 30% | - Leaves and absences
|
Just as I have just mentioned, almost all of our customers have passed the exam as well as getting the related certification easily with the help of our PF1 exam torrent, we strongly believe that it is impossible for you to be the exception. So choosing our Payroll Fundamentals 1Exam exam question actually means that you will have more opportunities to get promotion in the near future, at the same time, needless to say that you will get a raise in pay accompanied with the promotion. What’s more, when you have shown your talent with Payroll Fundamentals 1Exam certification in relating field, naturally, you will have the chance to enlarge your friends circle with a lot of distinguished persons who may influence you career life profoundly. So why are you still hesitating for purchasing our PF1 Guide Torrent? Your bright future is starting from here!
NEW QUESTION # 41
A paper Record of Employment must be issued:
Answer: A
Explanation:
Service Canada's ROE guidance states that an employer must issue an ROE each time an employee experiences an interruption of earnings and when Service Canada requests one. This makes option A true.
For paper ROEs, the ROE guide is explicit about deadlines: you must issue a paper ROE within 5 calendar days of (1) the first day of an interruption of earnings, or (2) the day the employer becomes aware that an interruption of earnings has occurred. This confirms option B.
An interruption of earnings generally occurs under the 7-day rule-when an employee has had or is anticipated to have 7 consecutive calendar days with no work and no insurable earnings from the employer.
That's why option C is also true: once the employer becomes aware the 7-day threshold is met (or will be met), the ROE requirement is triggered, and the paper ROE must be issued within the time limit above.
NEW QUESTION # 42
Benefits are:
Answer: B
Explanation:
In Canadian payroll, a benefit generally means the employer has provided something of value to the employee (or paid for something on the employee's behalf), rather than paying cash for work performed. The CRA's Employers' Guide - Taxable Benefits and Allowances (T4130)explains that a benefit/allowance may be provided in cash (for example, an allowance) or in a manner other than cash (for example, a parking space or gift), and that employers may have to include the value of that benefit/allowance in the employee's income depending on the circumstances.
Option C best captures this "value of something provided or paid for" concept. Option B describes wages
/salary (earnings for work). Option A aligns more with reimbursements/expense coverage. Option D aligns with allowances for business use of personal property (often treated separately and may be taxable or non- taxable depending on CRA rules and documentation). Payroll's role is to determine whether the benefit is taxable, value it correctly, and apply the right statutory withholdings and reporting.
NEW QUESTION # 43
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
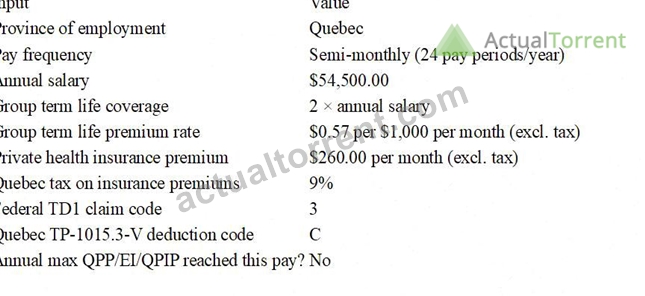
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases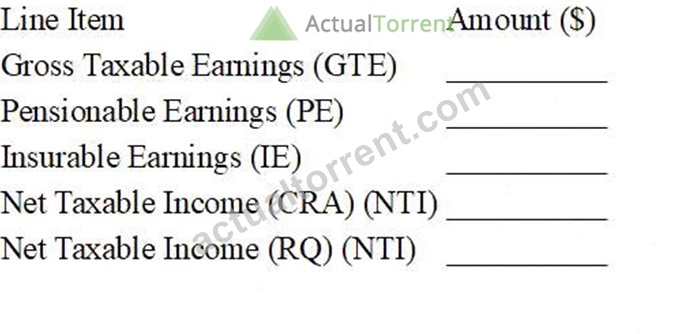
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
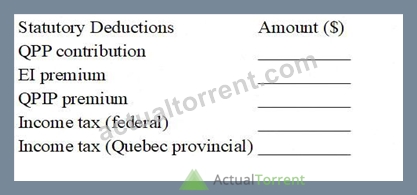
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
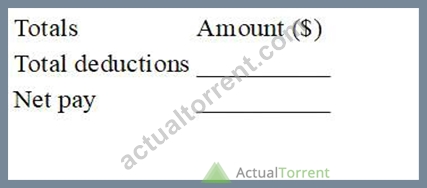
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 44
Which statutory deductions is salary continuance subject to?
Answer: D
Explanation:
Salary continuance means the employee continues to receive regular pay (and often benefits) for a period after their job ends. In this arrangement, the payments are treated like regular employment income for payroll purposes, so the usual payroll deductions apply. A Government of Canada guidance page explains that when severance is paid as salary continuance, the employee pays income tax like regular employment income and that the usual deductions apply, including CPP (or QPP), EI premiums, and RPP contributions (where applicable).
This aligns with standard payroll obligations in CRA's payroll remittance framework: employers deduct and remit CPP contributions, EI premiums, and income tax on employment income unless a specific exemption applies.
Therefore, the correct option is B (All deductions)-and in Quebec, that "all deductions" concept includes Quebec-specific programs (for example QPP/QPIP where applicable) based on the employee's province of employment and insurability rules.
NEW QUESTION # 45
When is the government-prescribed rate of interest set?
Answer: D
Explanation:
The CRA's prescribed interest rates are established for specific periods labelled by calendar quarter (for example, "first calendar quarter 2026"), and CRA publishes the rate schedule by quarter.
This prescribed rate is used in multiple tax contexts, including calculating taxable benefits on certain interest- free or low-interest employee/shareholder loans, and it also relates to interest charged/paid by the CRA on overdue amounts and overpayments (with different rates for different situations).
Because CRA's publication is organized and effective by quarter (e.g., Jan 1-Mar 31; Apr 1-Jun 30; Jul 1- Sep 30; Oct 1-Dec 31), the correct answer is each calendar quarter (option D), not monthly, semi-annual, or annual.
NEW QUESTION # 46
......
Owning the ActualTorrent PF1 exam certification training materials is equal to have a bright future, and equal to own the key to success. After you purchase ActualTorrent's PF1 certification exam training materials, we will provide one year free renewal service. If there's any quality problem in PF1 Exam Dumps or you fail PF1 exam certification, we will give a full refund unconditionally.
PF1 Valid Test Vce Free: https://www.actualtorrent.com/PF1-questions-answers.html
DOWNLOAD the newest ActualTorrent PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1HblpJ6gPYdOxZH3Jjgx0wq0N2NbHA0JL