無料でクラウドストレージから最新のPassTest CPHRM PDFダンプをダウンロードする:https://drive.google.com/open?id=1JSAB2v11ro9o27UqyHm9lvXY9RPE1xGe
ASHRMのCPHRMの試験の資料やほかのトレーニング資料を提供しているサイトがたくさんありますが、ASHRMのCPHRMの認証試験の高品質の資料を提供しているユニークなサイトはPassTestです。PassTestのガイダンスとヘルプを通して、初めにASHRMのCPHRM「Certified Professional in Health Care Risk Management (CPHRM)」の認証を受けるあなたは、気楽に試験に合格すことができます。PassTestが提供した問題と解答は現代の活力がみなぎる情報技術専門家が豊富な知識と実践経験を活かして研究した成果で、あなたが将来IT分野でより高いレベルに達することに助けを差し上げます。
| Certification Vendor: | American Hospital Association Certification Center (AHA-CC) / ASHRM |
|---|---|
| Exam Name: | CPHRM Certification Examination |
| Exam Number: | CPHRM |
| Real Exam Qty: | 175 multiple-choice (150 scored + 25 unscored pretest) |
| Certificate Validity Period: | 3 years |
| Exam Duration: | 180 minutes |
| Passing Score: | Scaled score 500 (scale 200–800) |
| Available Languages: | English |
| Exam Price: | $275–$400 USD (varies by membership status and region) |
| Exam Format: | Multiple-choice, Computer-based testing |
| Recommended Training: | ASHRM CPHRM Exam Preparation Course AHA Certification Preparation Resources |
| Exam Registration: | AHA Certification Center CPHRM Registration PSI Online Exam Scheduling |
| Sample Questions: | ASHRM CPHRM Sample Questions |
| Exam Way: | Computer-based testing delivered at PSI testing centers or online proctored format (depending on region) |
| Pre Condition: | Recommended: at least 3 years of experience in healthcare risk management or related healthcare field |
| Official Syllabus URL: | https://www.aha.org/certification-center/cphrm |
CPHRM試験問題は、学習結果を検出するためのさまざまな自己学習および自己評価機能を備えたソフトウェアを提供します。統計レポート機能は、学生が弱点を見つけて対処するのに役立つように提供されています。当社のソフトウェアには、時間制限やシミュレートされたテスト機能など、多くの新しい機能も搭載されています。速度を調整してアラートを維持できるCPHRMテストガイドでシミュレーションテストタイマーを設定したら、知識を習得するために心を傾けることができます。この関数がCPHRM試験の合格に役立つことは間違いありません。
| トピック | 出題範囲 |
|---|---|
| トピック 1 |
|
| トピック 2 |
|
| トピック 3 |
|
| トピック 4 |
|
| トピック 5 |
|
質問 # 17
An organization has recently changed insurance. The risk manager receives a claim from a former patient on July 3, 2004, claiming injury and alleging negligence by the surgery staff on September 5, 2003. Which of the following would apply to this claim?
* a claims-made policy for the period 1/1/03 to 1/1/04 with a retro date of 1/1/02
* an occurrence policy for the period 1/1/03 to 1/1/04
* a claims-made policy for the period 1/1/03 to 1/1/04 with a 1-year tail coverage
* an occurrence policy for the period 1/1/04 to 1/1/05
正解:D
解説:
According to Health Care Risk Management standards supported by ASHRM and the American Hospital Association Certification Center, coverage determination depends on both the policy trigger and relevant dates. The alleged negligence occurred on September 5, 2003. Under an occurrence policy in effect from 1/1
/03 to 1/1/04, coverage applies because the event occurred during that policy period, regardless of when the claim was filed. Therefore, option 2 applies.
For a claims-made policy covering 1/1/03 to 1/1/04, coverage would require that the claim be made and reported during the policy period unless tail coverage is in place. Because the claim was received on July 3,
2004, after expiration of the 1/1/03 to 1/1/04 claims-made policy, coverage would apply only if a 1-year tail was purchased. Thus, option 3 applies.
Option 1 would not apply because the claim was made after the claims-made policy period ended, and no tail is specified. Option 4 would not apply because occurrence coverage from 1/1/04 to 1/1/05 would not cover an event that occurred in 2003.
Risk financing objectives emphasize understanding policy triggers, reporting requirements, and tail coverage.
Therefore, the applicable coverage scenarios are the occurrence policy for 2003 and the claims-made policy with tail coverage.
質問 # 18
The following is a table of expense and indemnity figures for an organization's last 6 years.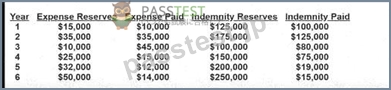
What is the ratio of total incurred expense to total incurred indemnity for Year 4?
正解:A
解説:
According to Health Care Risk Management principles supported by ASHRM and the American Hospital Association Certification Center, total incurred amounts include both paid amounts and reserves. Incurred expense equals expense paid plus expense reserves. Incurred indemnity equals indemnity paid plus indemnity reserves.
For Year 4:
Total incurred expense = $25,000 reserves + $15,000 paid = $40,000.
Total incurred indemnity = $150,000 reserves + $75,000 paid = $225,000.
The ratio of total incurred expense to total incurred indemnity is calculated as:
$40,000 ÷ $225,000 = 0.1778, which rounds to approximately 0.18.
However, among the answer options provided, the closest value is 0.20 only if rounded broadly. Since precise calculation yields approximately 0.18, the mathematically correct ratio is approximately 0.18.
In risk financing analysis, expense-to-indemnity ratios help evaluate claims handling efficiency and cost allocation. Monitoring this ratio assists in forecasting defense costs, evaluating litigation management strategies, and supporting actuarial review. Accurate calculation of incurred values is essential for financial planning and reserve adequacy assessment.
質問 # 19
A doctor fails to administer an indicated test, and the patient deteriorates and must be admitted. This is an example of:
正解:A
解説:
Failing to order or perform an indicated test can represent a diagnostic process failure-an omission that delays recognition of deterioration, leading to harm and escalation of care. Risk management objectives treat diagnostic safety as a systems issue: access to decision support, timely follow-up of abnormal results, clear responsibility for test ordering and review, effective handoffs, and adequate staffing/workload conditions to avoid missed steps. Such errors are often linked to underuse in the IOM quality framework (failure to provide beneficial service) and can drive claims due to preventable worsening. Preventive strategies include standardized pathways, trigger tools for abnormal labs, closed-loop test result management, and teamwork practices that encourage escalation when clinical concern persists despite uncertainty.
質問 # 20
Which of the following documents will an insurance underwriter use to provide an insurance quote?
正解:A
解説:
Under Health Care Risk Management principles supported by ASHRM and the American Hospital Association Certification Center, the insurance application is the primary document used by an underwriter to evaluate risk and generate a premium quote. The application provides detailed information about the organization's operations, services, patient volume, claims history, risk control measures, governance structure, and prior insurance coverage. This information enables the underwriter to assess exposure, determine eligibility, and calculate appropriate pricing and coverage terms.
A certificate of insurance is issued after a policy is in force to verify coverage to third parties and does not serve as a quoting document. The declaration page is part of an existing insurance policy and summarizes coverage limits, deductibles, and endorsements; it reflects finalized terms rather than information used to generate a quote. A certificate of need is a regulatory document related to state approval of healthcare facilities or services and is unrelated to underwriting.
Risk financing objectives emphasize accurate disclosure and thorough completion of insurance applications, as misrepresentation or omission may affect coverage validity. Therefore, the application is the document used by an underwriter to provide an insurance quote.
質問 # 21
The first layer of insurance that will respond to a specific type of loss or exposure is called
正解:C
解説:
According to Health Care Risk Management principles supported by ASHRM and the American Hospital Association Certification Center, insurance coverage for liability exposures is often structured in layers. The first layer of insurance that responds to a covered loss is known as the primary policy.
Primary insurance provides initial coverage once any applicable deductible or self-insured retention has been satisfied. It is responsible for defense and indemnity payments up to the policy's stated per-occurrence and aggregate limits. Only after the primary policy limits are exhausted do excess or umbrella policies respond.
Terms such as baseline, foundation, and frontline are not recognized technical classifications in layered insurance structures. In professional and general liability programs, organizations commonly maintain a primary layer followed by one or more excess layers to protect against catastrophic losses.
Risk financing objectives emphasize understanding policy structure, limits, attachment points, and coordination between layers to ensure adequate protection of organizational assets. Therefore, the correct term for the first layer of insurance that responds to a loss is the primary policy.
質問 # 22
......
CPHRM試験対応: https://www.passtest.jp/ASHRM/CPHRM-shiken.html
2026年PassTestの最新CPHRM PDFダンプおよびCPHRM試験エンジンの無料共有:https://drive.google.com/open?id=1JSAB2v11ro9o27UqyHm9lvXY9RPE1xGe