P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by VCEDumps: https://drive.google.com/open?id=16ftCd0AanMXsYNKkU1PXZf7DgP4RDGZZ
When you decide to pass ClaimCenter-Business-Analysts exam, you must want to find a good study materials to help you prepare for your exam. If you decide to choice our products as your study tool, you will be easier to pass your exam and get the ClaimCenter-Business-Analysts certification in the shortest time. So do not hesitate and buy our ClaimCenter-Business-Analysts Test Torrent, an unexpected surprise is awaiting you, we believe you will prefer to our ClaimCenter-Business-Analysts test questions than other study materials. In order to let you understand our ClaimCenter-Business-Analysts exam prep in detail, we are going to introduce our products to you.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
>> Latest ClaimCenter-Business-Analysts Practice Questions <<
There are more opportunities for possessing with a certification, and our ClaimCenter-Business-Analysts study tool is the greatest resource to get a leg up on your competition. When it comes to our time-tested ClaimCenter-Business-Analysts latest practice materials, for one thing, we have a professional team contains a lot of experts who have devoted themselves to development of our ClaimCenter-Business-Analysts Exam Guide, thus we feel confident enough under the intensely competitive market. For another thing, conforming to the real exam our ClaimCenter-Business-Analysts study tool has the ability to catch the core knowledge. So our customers can pass the exam with ease.
NEW QUESTION # 43
When capturing information about a damaged vehicle, Succeed Insurance requires that the total distance driven (miles/km) for the vehicle be captured as well. What is the best practice for a Business Analyst (BA) to determine if ClaimCenter already has a field to capture distance driven?
Answer: A
Explanation:
The Data Dictionary is the definitive reference tool for Business Analysts to explore the data model of a Guidewire application.
* Best Practice:To determine if a specific data point (like "distance driven" or "odometer reading") exists in the system's schema, the BA should consult theData Dictionary. This auto-generated documentation lists all entities (such as Vehicle or VehicleIncident) and their associated fields (columns), along with data types and descriptions. This confirms existence even if the field is not currently exposed on the user interface.
* Why Option B is better than A:Checking the UI (Option A) is unreliable because a field may exist in the database but be hidden, disabled, or not placed on the specific screen the BA is viewing.
* Why Option B is better than C:The Application Guide (Option C) describes standard features and workflows but does not provide a granular, technical list of every database column, nor does it reflect any custom schema extensions added by the implementation team.
* Why Option B is better than D:While Guidewire Studio (Option D) is a powerful tool thatcanverify this, it is primarily a developer environment. For a Business Analyst, the Data Dictionary is the intended, accessible "Source of Truth" artifact for data modeling questions without requiring IDE access or technical code navigation.
NEW QUESTION # 44
A claim for an auto accident in California has been assigned to an insurance Adjuster in the Midwest region for investigation and processing. The claim has been flagged as "Low Complexity" in ClaimCenter. The Adjuster has an authority limit for total reserves of $30,000 and has created reserves totaling $35,000.
What is the correct approval routing for this transaction?
Answer: D
Explanation:
Based on theGuidewire ClaimCenter Financials and Authority Limitsdocumentation, the correct behavior for this scenario is determined by the strict enforcement ofAuthority Limits, regardless of claim complexity or geographic region.
In ClaimCenter, every user is assigned specific authority limits for various financial transactions, including reserves, payments, and recovery reserves. These limits are absolute constraints designed to control financial exposure. In the scenario provided, the Adjuster attempted to set a reserve of$35,000, which exceeds their authorized limit of$30,000.
When a user submits a financial transaction that exceeds their pre-configured authority limit, ClaimCenter automatically triggers anApproval Workflow. The system validates the transaction amount against the user's limit at the time of submission. Since the limit is breached, the transaction is not committed immediately to the database as "Submitted"; instead, it enters a"Pending Approval"status.
Routing Logic:
The standard, out-of-the-box approval routing logic in ClaimCenter follows the Group Hierarchy.
* The system identifies the group to which the Adjuster belongs.
* It creates anApproval Activity.
* This activity is assigned to theSupervisorof that group.
The Supervisor must then review the transaction. If the Supervisor has sufficient authority (greater than
$35,000), they can approve it. If the Supervisor also lacks sufficient authority, they must still "approve" it to escalate the request further up the hierarchy totheirmanager, until it reaches a user with sufficient limits.
Why other options are incorrect:
* A (Complexity):Claim complexity flags (e.g., "Low Complexity") are often used forAssignmentrules (Segment-based assignment) or straight-through processing ofdocuments, but they do not override Financial Authoritycontrols. A low-complexity claim still requires financial oversight if the dollar amount is high.
* B (Peer Approval):Approval routing is hierarchical, not peer-to-peer. It does not look for "any" team member; it looks specifically for the defined Supervisor.
* C (Region):The region mismatch might trigger an assignment rule or a validation warning depending on configuration, but the specific trigger for theapprovalhere is purely the financial discrepancy ($35k
> $30k), not the geography.
NEW QUESTION # 45
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.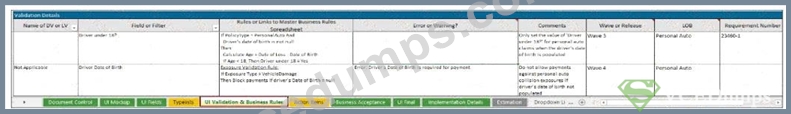
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: D,E
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 46
A performing arts organization operates nationwide and is responsible for setting up stages for musical acts and concerts. The organization requires specific insurance coverage for its gear and equipment, including audio systems, lighting, cameras, and control boards. Succeed Insurance wants to optimize claim intake, processing, and reporting for this organization.
Which modifications should be made to ClaimCenter's base product line of business (LOB)?
Answer: D
Explanation:
According to the Guidewire ClaimCenter Business Analyst documentation, ClaimCenter's line of business (LOB) framework is intentionally designed to support extensibility through configuration rather than structural changes to core policy or loss classification elements. When an insurer needs to support specialized insured property-such as professional audio, lighting, and staging equipment-the recommended approach is to enhance the coverage configuration.
ClaimCenter models policy coverage using a hierarchy ofCoverageTypeandCoverage Subtypetypelists.
CoverageType codes represent high-level coverage categories defined by the policy, while Coverage Subtype codes allow insurers to further refine and classify coverage details. These coverage elements are then associated withExposureTypecodes, which drive claim processing behavior such as exposure creation, reserving, payment handling, and reporting.
By adding appropriate CoverageType and Coverage Subtype codes for equipment and gear coverage and mapping them to ExposureType codes, ClaimCenter can automatically create accurate exposures during claim intake. This approach ensures adjusters can efficiently process claims while maintaining consistent workflows and financial controls. It also supports meaningful analytics and reporting without altering the base product structure.
The Guidewire documentation advises against introducing newLossTypeorPolicyTypecodes unless the insurer is defining an entirely new policy or loss classification. LossType codes describe how a loss occurred (for example, theft or accidental damage), not the nature of the insured property. PolicyType changes are similarly broad and unnecessary for extending coverage within an existing LOB.
Therefore, optionBaligns with Guidewire best practices by extending ClaimCenter's coverage and exposure configuration to meet the organization's needs while preserving the integrity of the standard LOB model.
NEW QUESTION # 47
A car accident in a rural area of Durango, Colorado is reported to Succeed Insurance. The driver of the damaged car reportedly hit the base of a windmill tower while driving at night. There was no other passenger in the car when the accident happened, and the driver has a valid auto policy on file.
While the driver is not physically injured, the entire passenger side of the car has been severely damaged.
Although the windmill is still functioning, the base of the tower has sustained multiple broken parts.
Which two incidents need to be created for the claim based on the reported accident? (Choose two.)
Answer: D,E
Explanation:
In Guidewire ClaimCenter, an Incident is the data object used to capture the specific facts about "what" was damaged or affected during the loss event. It serves as the foundation for creating Exposures (the financial liabilities).
* Vehicle Incident (Option C):The scenario states that the insured's car has been "severely damaged" on the passenger side. To record these facts-including the point of impact, the severity, and the vehicle description-the Adjuster must create aVehicle Incident. This incident will eventually support the collision coverage exposure.
* Property Incident (Option B):The accident involved the car hitting a "windmill tower," resulting in
"broken parts" to the base. In ClaimCenter, damage to third-party non-vehicular objects (like fences, poles, buildings, or towers) is captured using aFixed Property Incident(often referred to generically as a Property Incident). This incident records the damage description and ownership of the windmill, which is necessary to handle the Property Damage Liability claim.
Why other options are incorrect:
* Option E (Injury):The scenario explicitly states the driver is "not physically injured." Therefore, an Injury Incident is not required.
* Option A ("Another structure"):The standard object for third-party fixed property damage is the Property Incident/Fixed Property Incident, not "Another structure."
* Option D (Loss of Use):While possible later, the primary immediate damage is physical. Loss of Use is usually a secondary exposure type, not the primary incident definition for the tower itself.
NEW QUESTION # 48
......
With constantly updated Guidewire pdf files providing the most relevant questions and correct answers, you can find a way out in your industry by getting the ClaimCenter-Business-Analysts certification. Our ClaimCenter-Business-Analysts test engine is very intelligence and can help you experienced the interactive study. In addition, you will get the scores after each ClaimCenter-Business-Analysts Practice Test, which can make you know about the weakness and strengthen about the ClaimCenter-Business-Analysts real test , then you can study purposefully.
ClaimCenter-Business-Analysts Free Updates: https://www.vcedumps.com/ClaimCenter-Business-Analysts-examcollection.html
BONUS!!! Download part of VCEDumps ClaimCenter-Business-Analysts dumps for free: https://drive.google.com/open?id=16ftCd0AanMXsYNKkU1PXZf7DgP4RDGZZ