BTW, DOWNLOAD part of PracticeVCE Accounting-for-Decision-Makers dumps from Cloud Storage: https://drive.google.com/open?id=1nZFOE12FAPbgLUGQCsmWTWCfjqmc3-Wp
As we know, our products can be recognized as the most helpful and the greatest WGU Accounting-for-Decision-Makers test engine across the globe. Even though you are happy to hear this good news, you may think our price is higher than others. We can guarantee that we will keep the most appropriate price because we want to expand our reputation of WGU Accounting-for-Decision-Makers Preparation test in this line and create a global brand about the products.
| Section | Objectives |
|---|---|
| Topic 1: Decision Making and Performance Evaluation | - Make-or-buy and special order decisions - Capital budgeting techniques (NPV, IRR, Payback Period) - Balanced Scorecard concepts - Relevant costs for decision making - Responsibility accounting and performance metrics |
| Topic 2: Managerial Accounting Concepts | - Cost classification and behavior (fixed, variable, mixed costs) - Cost-Volume-Profit (CVP) analysis - Job order and process costing - Contribution margin and break-even analysis |
| Topic 3: Financial Statement Analysis | - Interpreting financial data for decision-making purposes - Horizontal and vertical analysis - Ratio analysis (liquidity, profitability, solvency, efficiency ratios) |
| Topic 4: Budgeting and Planning | - Operating budgets (sales, production, direct materials, direct labor, overhead) - Variance analysis - Master budget components - Financial budgets (cash budget, budgeted income statement, budgeted balance sheet) |
| Topic 5: Financial Accounting Fundamentals | - Understanding the accounting cycle - Accrual vs. cash basis accounting - Preparing financial statements (Income Statement, Balance Sheet, Statement of Cash Flows) - Recording transactions and adjusting entries |
>> Accounting-for-Decision-Makers Sure Pass <<
The Accounting-for-Decision-Makers would assist applicants in preparing for the WGU Accounting-for-Decision-Makers exam successfully in one go Accounting-for-Decision-Makers would provide Accounting-for-Decision-Makers candidates with accurate and real WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) Dumps which are necessary to clear the Accounting-for-Decision-Makers test quickly. Students will feel at ease since the content they are provided with is organized rather than dispersed.
NEW QUESTION # 21
What does it mean if a company has a debt ratio of 101.5%?
Answer: B
NEW QUESTION # 22
A company presently uses traditional volume-based costing to allocate overhead to its products.
The following table provides information on two of the company's products:
Product A
Product B
Selling price
$8
$12
Direct material
$2
$3
Direct labor
$1
$2
Applied overhead
$3
$4
Gross margin
$2
$3
Overhead that would be applied to Product A would increase to $8 per unit after identifying cost pools and cost drivers, and the overhead applied to Product B would drop to $2 per unit .
How would this change in the way overhead is allocated affect the selling price of both products?
Answer: C
Explanation:
The correct answer is C . Under activity-based costing (ABC) , overhead is reassigned based on the activities that actually drive cost consumption. ABC often reveals that one product was previously undercosted while another was overcosted under traditional volume-based allocation. OpenStax explains that ABC can shift overhead between products and provide more accurate product-cost information for pricing and decision- making.
For Product A , the new overhead rises from $3 to $8 , increasing total unit cost from $6 ($2 + $1 + $3) to
$11 ($2 + $1 + $8). Since the current selling price is only $8 , Product A is now shown as underpriced, so its selling price would likely need to increase . For Product B , overhead falls from $4 to $2 , reducing total unit cost from $9 to $7 . With a current selling price of $12 , Product B appears more profitable than previously believed, so management could choose to decrease its price if needed for competitive reasons. Therefore, the most logical result is Product A price up, Product B price down , which is Option C .
NEW QUESTION # 23
Which balance sheet category reflects what a company owns that can be turned into cash or used to generate cash?
Answer: C
Explanation:
The correct answer is A. Assets . Assets are economic resources a business owns or controls that can either be converted into cash or used to help generate future cash inflows. Accounting references describe assets as items a business owns, including current assets such as cash, accounts receivable, and inventory, as well as long-term assets like equipment, buildings, and intangible assets that support future operations.
Option B, liabilities , refers to obligations or amounts the business owes to others, not what it owns. Option C, revenues , represents inflows earned from providing goods or services during a period and is an income statement category, not a balance sheet resource category. Option D, owners' equity , reflects the residual interest of the owners after liabilities are deducted from assets. Because the question asks about what the company owns and what can be turned into cash or used to generate cash, the most accurate balance sheet category is assets. Current assets are especially important because they are closest to cash, but the broader correct category remains Assets . Therefore, Option A is the right answer.
NEW QUESTION # 24
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.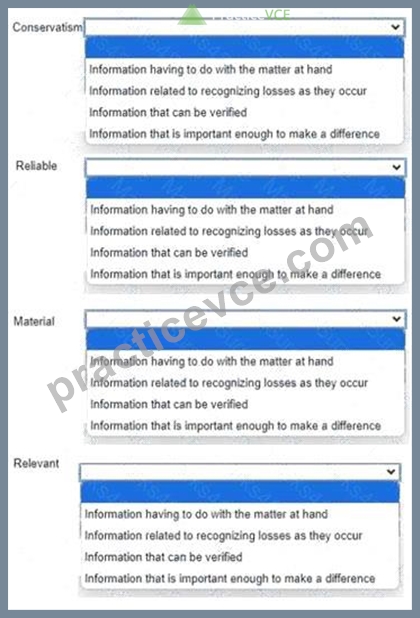
Answer:
Explanation: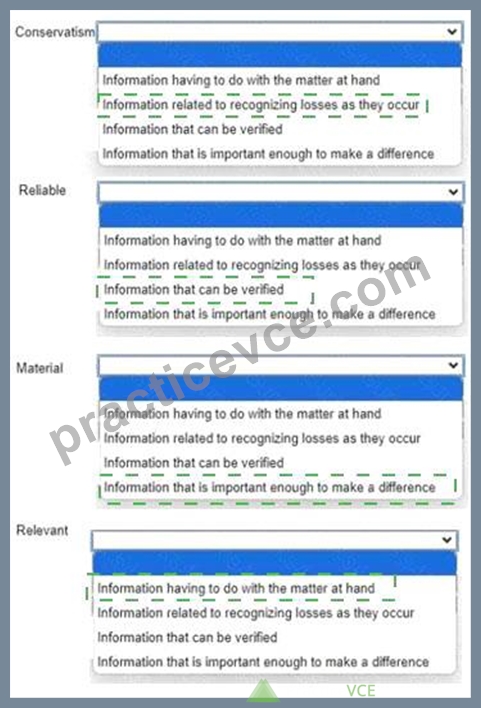
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 25
Which two item subtotals are included in a multi-step income statement?
Choose 2 answers.
Answer: B,D
Explanation:
The correct answers are A. Gross profit and B. Income from operations . A multi-step income statement separates operating and nonoperating activities and includes intermediate subtotals that help users analyze profitability in stages. Two of the most important subtotals are gross profit and income from operations .
Gross profit is calculated as net sales minus cost of goods sold , while income from operations is determined after subtracting operating expenses from gross profit. OpenStax explains that a multi-step income statement includes these subtotals to give users more insight into business performance.
Options C. Current liabilities and D. Total assets are incorrect because those belong on the balance sheet , not the income statement. A multi-step income statement focuses on revenues, costs, and expenses for a period of time, not financial position at a point in time. By providing subtotals such as gross profit and income from operations, the statement helps managers, investors, and creditors evaluate how well the company performs in its core operations before considering nonoperating items. Therefore, the correct choices are A and B .
NEW QUESTION # 26
......
You only need 20-30 hours to practice our software materials and then you can attend the exam. It costs you little time and energy. The Accounting-for-Decision-Makers exam questions are easy to be mastered and simplified the content of important information. The WGU Accounting for Decision Makers C213 VAC2 test guide conveys more important information with amount of answers and questions, thus the learning for the examinee is easy and highly efficient. The language which is easy to be understood and simple, Accounting-for-Decision-Makers Exam Questions are suitable for any learners no matter he or she is a student or the person who have worked for many years with profound experiences. So it is convenient for the learners to master the Accounting-for-Decision-Makers guide torrent and pass the exam in a short time. The amount of the examinee is large.
Free Accounting-for-Decision-Makers Dumps: https://www.practicevce.com/WGU/Accounting-for-Decision-Makers-practice-exam-dumps.html
DOWNLOAD the newest PracticeVCE Accounting-for-Decision-Makers PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1nZFOE12FAPbgLUGQCsmWTWCfjqmc3-Wp