BONUS!!! Download part of Dumps4PDF IFC dumps for free: https://drive.google.com/open?id=1ziX-rzmX2jdlNcPzLozaHKZ0imNQUxFS
These Investment Funds in Canada (IFC) Exam (IFC) practice exams contain all the IFC questions that clearly and completely elaborate on the difficulties and hurdles you will face in the final Investment Funds in Canada (IFC) Exam (IFC) exam. Investment Funds in Canada (IFC) Exam (IFC) practice test is customizable so that you can change the timings of each session. Dumps4PDF desktop CISI IFC Practice Test questions software is only compatible with windows and easy to use for everyone.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Introduction to the Mutual Funds Marketplace | 13% | |
| Topic 2: Understanding Alternative Managed Products | 3% | |
| Topic 3: Understanding Investment Products and Portfolios | 18% | |
| Topic 4: Know Your Client (KYC) Communication Process | 19% | |
| Topic 5: The Modern Mutual Fund | 5% | |
| Topic 6: Ethics, Compliance, and Mutual Fund Regulation | 16% | |
| Topic 7: Analysis of Mutual Funds | 10% | |
| Topic 8: Evaluating and Selecting Mutual Funds | 16% |
Our CISI IFC Practice Exam software is compatible with Windows computers. If you run into any issues while using our Investment Funds in Canada (IFC) Exam (IFC) exam simulation software, our 24/7 product support team is here to help you. One of our IFC desktop practice exam software's other feature is that it can be used even without an active internet connection. The Internet is only required for product license validation. This feature allows users to practice without an active internet connection.
NEW QUESTION # 252
What type of investment account has the option to open it with rights of survivorship?
Answer: A
Explanation:
Rights of survivorship means that if one account holder dies, their share of the assets automatically transfers to the surviving holder(s).
This feature is available in joint non-registered accounts.
Registered accounts (A) (e.g., RRSP, TFSA) are individual accounts and cannot be opened jointly with rights of survivorship.
Trust accounts (B) follow trust law, not survivorship rules.
Corporate accounts (D) belong to the company, not individuals.
NEW QUESTION # 253
Davis invested in a tactical asset allocation fund in his non-registered investment account. Distributions from the mutual fund are paid directly to Davis and not reinvested. Assuming a federal marginal tax rate of 26%, dividend gross-up rate of 38% and federal dividend tax credit rate of 15%, which type of distribution would result in the lowest amount of tax payable?
Answer: B
Explanation:
An eligible dividend is a type of dividend that is paid by a Canadian corporation that meets certain criteria and is eligible for the enhanced dividend tax credit. The dividend tax credit reduces the amount of tax payable on dividends by providing a credit against the tax liability. An eligible dividend has a higher gross-up rate and a higher dividend tax credit rate than a non-eligible dividend, which means that it results in a lower effective tax rate. A capital dividend is a type of dividend that is paid from the capital gains realized by a corporation and is tax-free to the shareholder. However, a tactical asset allocation fund is unlikely to pay capital dividends, as they are usually reserved for private corporations. A capital gain is the profit from selling an asset at a higher price than its purchase price. Only 50% of the capital gain is taxable, which means that it has a lower effective tax rate than interest income, which is fully taxable. However, a capital gain distribution from a mutual fund is not the same as a capital gain from selling the mutual fund units. A capital gain distribution is paid when the fund realizes a capital gain from selling its underlying assets, and it is taxable in the year it is received, regardless of whether the shareholder sells the fund units or not. Therefore, it does not benefit from the deferral of tax that occurs when the shareholder sells the fund units at a later date. An interest distribution is paid when the fund earns interest income from its underlying assets, such as bonds or money market instruments. Interest income is fully taxable at the marginal tax rate, which means that it has the highest effective tax rate among the four types of distributions.
To compare the amount of tax payable for each type of distribution, we can use the following formula:
Tax=(Distribution×Gross#up)×MarginalTaxRate#(Distribution×Gross#up)×DividendTaxCreditRate For simplicity, we assume that Davis receives $100 of each type of distribution and that he does not have any other income or deductions. We also ignore any provincial taxes or credits. Using the formula, we can calculate the tax payable for each type of distribution as follows:
* Capital Dividend:Tax=(100×0)×0.26#(100×0)×0=0
* Capital Gain:Tax=(100×0.5)×0.26#(100×0.5)×0=13
* Eligible Dividend:Tax=(100×1.38)×0.26#(100×1.38)×0.15=10.14
* Interest:Tax=(100×1)×0.26#(100×1)×0=26
Therefore, an eligible dividend would result in the lowest amount of tax payable, followed by a capital gain, a capital dividend, and an interest distribution.
:
Canadian Investment Funds Course (CIFC) Study Guide, Chapter 7: Taxation, Section 7.2: Taxation of Investment Income, page 7-41 Eligible Dividends Definition - Investopedia2 Capital Dividend Definition - Investopedia3 Capital Gain Distribution Definition - Investopedia4
NEW QUESTION # 254
On January 3, John invests $500 in the Blue Sky U.S. Equity Fund. On July 1 of the same year, he invests another $500 into the same mutual fund. Information about the net asset value per unit (NAVPU) at the time of each transaction is provided below. Given this information, what will be the value of John's investment on December 31 of this year (please ignore transaction costs and distributions)?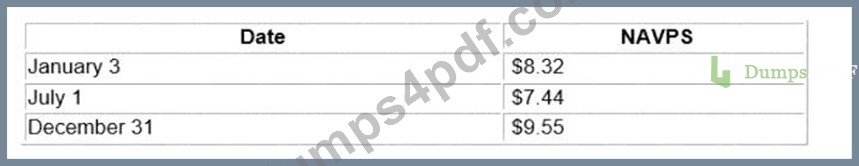
Answer: D
Explanation:
The value of John's investment on December 31 of this year can be calculated by multiplying the number of units he holds by the net asset value per unit (NAVPU) on that date. Since John invested $500 on January 3 and $500 on July 1, he holds a total of 125.6 units (62.8 units from the first investment and 62.8 units from the second investment). Therefore, the value of his investment on December 31 will be 125.6 units x $9.55 NAVPU = $1,256.
Canadian Investment Funds Course, Chapter 2: Mutual Funds1
NEW QUESTION # 255
Your client Gerard is 30 years old and plans to retire at age 65. He has a mutual fund portfolio of $40,000 in which he invests $1,500 monthly. Gerard's objective is to use these funds to meet the 20% down payment requirement to buy a house for $650,000.
What is Gerard's investment time horizon not considering market fluctuations?
Answer: D
Explanation:
Gerard's investment time horizon is the length of time he plans to hold his investment until he needs to use the money for his specific goal. In this case, Gerard's goal is to use his mutual fund portfolio to meet the 20% down payment requirement to buy a house for $650,000. Therefore, his investment time horizon is determined by how long it will take him to accumulate enough money in his portfolio to cover the down payment amount.
Assuming that Gerard does not withdraw any money from his portfolio and that his portfolio earns a constant annual rate of return of 6%, we can use the following formula to calculate how long it will take him to reach his goal:
FV=PV×(1+r)n+PMT×r(1+r)n#1
where:
* FV is the future value of the portfolio
* PV is the present value of the portfolio
* r is the annual interest rate
* n is the number of years
* PMT is the monthly payment
We can rearrange the formula to solve for n:
n=log(1+r)logPV+PMT×r1FV#PMT×r1
Plugging in the given values, we get:
n=log(1+0.06)log40,000+1,500×0.061130,000#1,500×0.061
n=4.98
Therefore, Gerard's investment time horizon is approximately 5 years, not considering market fluctuations.
This means that he will need to invest his money in a way that matches his risk tolerance and expected return for this time period.
:
Canadian Investment Funds Course (CIFC) Study Guide, Chapter 4: Mutual Funds, Section 4.6: Asset Allocation and Diversification, page 4-271 Future Value of an Annuity Definition - Investopedia2
NEW QUESTION # 256
When comparing mutual funds, what information would help a Dealing Representative determine a suitable mutual fund for a client?
Answer: C
Explanation:
B is correct because assessing historical differences in the rate of return per unit of risk of similar mutual funds helps a Dealing Representative to compare the performance and risk-adjusted returns of different mutual funds and select the most suitable one for a client's risk tolerance and investment objectives.
Comparing historical rates of return between different types of mutual funds (A) does not account for the risk involved in each type of fund. Referencing the fund code for each mutual fund that is being compared does not provide any information about the fund's characteristics, features, or suitability. The rights a client has if there is a desire to cancel the purchased mutual fund (D) are not relevant for determining a suitable mutual fund for a client.
NEW QUESTION # 257
......
Dumps4PDF is benefiting more and more candidates for our excellent IFC exam torrent which is compiled by the professional experts accurately and skillfully. We are called the best friend on the way with our customers to help pass their IFC exam and help achieve their dreaming certification. The reason is that we not only provide our customers with valid and Reliable IFC Exam Materials, but also offer best service online since we uphold the professional ethical. So you can feel relax to have our IFC exam guide for we are a company with credibility.
IFC Latest Exam Review: https://www.dumps4pdf.com/IFC-valid-braindumps.html
BTW, DOWNLOAD part of Dumps4PDF IFC dumps from Cloud Storage: https://drive.google.com/open?id=1ziX-rzmX2jdlNcPzLozaHKZ0imNQUxFS