In fact, our AFP-Exam-1 exam materials provide comprehensive customers service, and our commitment to users does not end at the point of sale. If you have any questions related to our AFP-Exam-1 exam materials, you can always consult our customer service. Our customer service is 24 hours online and will answer your questions in the shortest possible time. Our AFP-Exam-1 Exam Materials assure you that we will provide the best service before you pass the AFP-Exam-1 exam. ActualTestsQuiz will never disappoint you. Therefore, you can prepare real AFP-Exam-1 exams using the actual AFP-Exam-1 exam questions. This is indeed a huge opportunity. Don't miss it!
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Investment Planning - Tax Planning - Risk Management and Insurance - Estate Planning - Asset and Liability Management - Retirement Planning |
>> Reliable AFP-Exam-1 Exam Tips <<
The study system of our company will provide all customers with the best study materials. If you buy the AFP-Exam-1 latest questions of our company, you will have the right to enjoy all the AFP-Exam-1 certification training materials from our company. By updating the study system of the AFP-Exam-1 Training Materials, we can guarantee that our company can provide the newest information about the exam for all people. We believe that getting the newest information about the exam will help all customers pass the AFP-Exam-1 exam easily.
NEW QUESTION # 12
Kendrick, age 55, owns a successful small business, ZXC Inc., valued at $800,000. Kendrick has extensive savings outside of the business and would like to pass the company onto his son at some point in the future.
Kendrick expects the business to increase in value $25,000 per year. If Kendrick decides to use an estate freeze to reduce the amount of taxes he will be required to pay, his financial planner should recommend that he implement the estate freeze at which point in relation to gifting the business to his son?
Answer: D
NEW QUESTION # 13
Ram Patel, age 65, is meeting with his financial planner, Maria Romano, to complete a financial plan. Ram is retiring this year, and his company provides a defined benefit pension plan. Upon retirement, he has the choice of receiving $20,000 each year for 20 years or until death (whichever is earlier), or he can take
$304,300, which is the commuted value at retirement. Ram has confirmed that he will be transferring the commuted value to a LIRA. After further discovery, Maria suggests that they utilize a 5% market rate of return and project the funds to last 25 years. What should Maria update Ram's projected annual retirement income to?
Answer: C
Explanation:
Maria should update Ram's projected retirement income to approximately $21,591. The commuted value is
$304,300, and Ram will transfer it to a LIRA. Using a 5% annual market return over a 25-year payout period, the annuity-style payment calculation is based on amortizing the capital over the projection period. The annual payment is calculated as present value multiplied by the discount rate factor: $304,300 × 0.05 divided by 1 minus 1.05 to the negative 25. The result is approximately $21,591 per year. Option B is simply the original pension option and ignores the commuted-value projection. Option D is a rough estimate, and option A overstates the sustainable annual amount. AFP retirement analysis requires consistent assumptions for rate of return, payout period, and income timing before comparing pension alternatives. Study Guide focus:
pension commuted values, LIRA transfers, retirement income projections, present value, and annuity calculations. The comparison should also recognize that a projected LIRA withdrawal stream is not the same guarantee as a pension promise.
NEW QUESTION # 14
Ali wishes to retire in five years. His financial planner calculates that he needs to save an additional $40,000 to meet his retirement income objectives. What would Ali's financial planner advise him to do in order to meet his retirement income objectives?
Answer: D
Explanation:
With only five years until retirement, Ali's planner should recommend reducing current expenses and redirecting the freed cash flow to retirement savings. The short time horizon makes aggressive corrective strategies dangerous. Borrowing through a mortgage to invest introduces leverage risk and could worsen retirement security if markets underperform. Increasing equity exposure solely to chase a higher return may be inconsistent with the time horizon and risk capacity. Whole life insurance is not an efficient solution for a near-term retirement savings shortfall; it combines insurance and investment features but does not directly solve a five-year funding gap. Expense reduction is controllable, immediate, and aligned with the identified
$40,000 savings need. The planner should quantify how much monthly savings is required and monitor progress annually. Study Guide focus: retirement shortfall strategies, savings rate, time horizon, risk capacity, leverage risk, and expense management. The recommendation is conservative because the closer the retirement date, the less time Ali has to recover from investment error.
NEW QUESTION # 15
In order to increase the assets in Rebecca's retirement savings, her financial planner is considering making a number of recommendations. Prior to obtaining her current employment, she withdrew funds from her RRSP under the Lifelong Learning Plan to upgrade her skills. She has four annual installments remaining on her Lifelong Learning Plan withdrawal and a small amount of savings in a TFSA. Rebecca now works as a sales associate in a small clothing store that has a group RRSP program for all employees which matches employee contributions. Which recommendation provides the best long-term impact to grow her retirement savings?
Answer: D
Explanation:
The company group RRSP match is the strongest long-term retirement recommendation because it provides immediate additional savings from the employer. A matching contribution is effectively a guaranteed enhancement to Rebecca's retirement funding that she cannot replicate by simply transferring her TFSA or changing her asset mix. Repaying the Lifelong Learning Plan installments is required, but it does not create new employer-funded retirement capital. Maximizing equity exposure may improve expected return, but it must remain within risk tolerance and does not replace the value of free matching contributions. Transferring TFSA savings to an RRSP may produce a deduction, yet it sacrifices TFSA flexibility and does not address the employer match. The AFP planning priority is to capture available employer contributions first, then coordinate LLP repayments, TFSA use, and ongoing RRSP savings. Study Guide focus: group RRSPs, employer matching, LLP repayment, retirement accumulation, and savings prioritization. Missing the match would leave employer money unclaimed, which is rarely defensible when the employee can afford the contribution.
NEW QUESTION # 16
Consider the following information for a client's portfolio: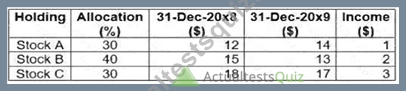
What is the annual rate of return for this portfolio?
Answer: C
Explanation:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
NEW QUESTION # 17
......
As is known to us, people who want to take the AFP-Exam-1 exam include different ages, different fields and so on. It is very important for company to design the AFP-Exam-1 exam prep suitable for all people. However, our company has achieved the goal. We can promise that the AFP-Exam-1 test questions from our company will be suitable all people. There are many functions about our study materials beyond your imagination. You can purchase our AFP-Exam-1 reference guide according to your own tastes. We believe that the understanding of our study materials will be very easy for you. We hope that you can choose the AFP-Exam-1 test questions from our company, because our products know you better.
Reliable AFP-Exam-1 Exam Preparation: https://www.actualtestsquiz.com/AFP-Exam-1-test-torrent.html