The pass rate is 98.75% for Financial-Management study materials, and if you choose us, we can ensure you pass the exam successfully. In addition, Financial-Management exam dumps of us are edited by professional experts, they are quite familiar with the exam center, therefore Financial-Management study materials cover most of knowledge points. We also pass guarantee and money back guarantee if you fail to pass the exam. We will refund your money to your payment account. Online service stuff for Financial-Management Exam Braindumps is available, and if you have any questions, you can have a chat with us.
| Section | Objectives |
|---|---|
| Topic 1: Financial Management Concepts | - Financial Markets and Institutions
|
| Topic 2: Capital Budgeting | - Decision Criteria
|
| Topic 3: Financial Statement Analysis | - Financial Statement Basics
|
| Topic 4: Cost of Capital and Capital Structure | - Cost of Capital
|
| Topic 5: Time Value of Money | - Bond and Stock Valuation
|
| Topic 6: Working Capital Management | - Current Liabilities Management
|
>> Guaranteed WGU Financial-Management Passing <<
In addition to the free download of sample questions, we are also confident that candidates who use Financial-Management Test Guide will pass the exam at one go. WGU Financial Management VBC1 prep torrent is revised and updated according to the latest changes in the syllabus and the latest developments in theory and practice. After you pass the exam, if you want to cancel your account, contact us by email and we will delete all your relevant information. Second, the purchase process of WGU Financial Management VBC1 prep torrent is very safe and transactions are conducted through the most reliable guarantee platform.
NEW QUESTION # 48
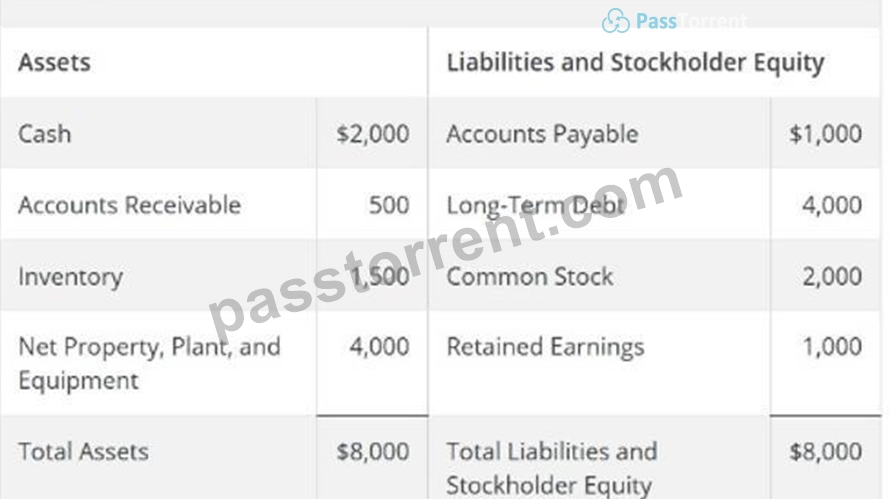
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'stotal asset turnoverfor 20X3?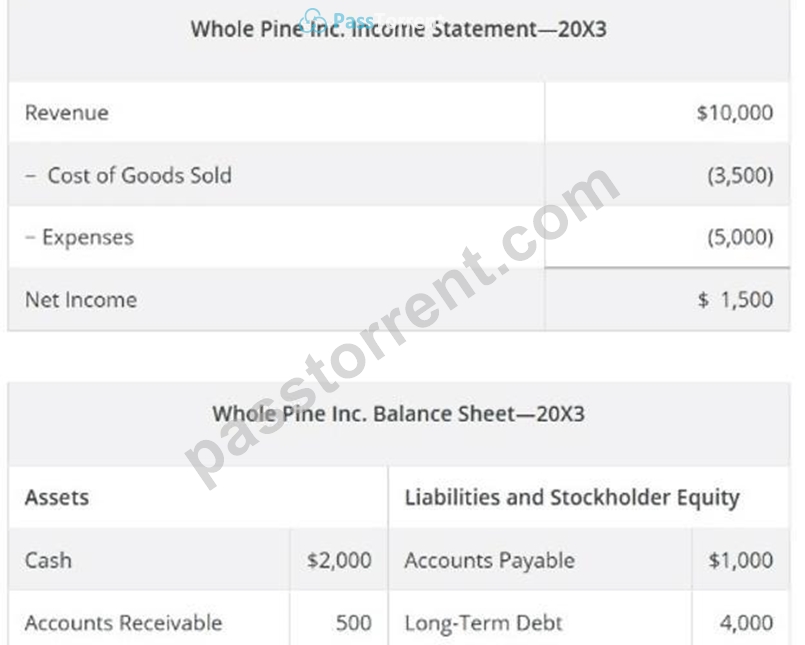
Answer: B
Explanation:
Total asset turnover measures how efficiently a firm uses its assets to generate revenue. It is calculated as Sales ÷ Total Assets. For Whole Pine Inc., sales for 20X3 are $10,000 and total assets are $8,000.
Dividing $10,000 by $8,000 yields a total asset turnover of 1.25. This means the company generates
$1.25 in sales for every $1.00 invested in assets. From a financial management perspective, this ratio is a key indicator of operating efficiency and is commonly compared across firms within the same industry or across time. A higher turnover suggests more efficient use of assets, while a lower turnover may indicate underutilized capacity or inefficient asset deployment. Asset turnover is also a component of the DuPont analysis, linking operational efficiency to return on equity. Option B correctly reflects both the calculation and interpretation consistent with standard financial analysis practice.
NEW QUESTION # 49
Why must analysts be cautious about accounting practices when analyzing ratios?
Answer: A
Explanation:
Accounting methods influence reported financial results and, consequently, financial ratios. Differences in depreciation methods, inventory valuation (FIFO vs. LIFO), revenue recognition, and expense capitalization can significantly alter earnings, assets, and equity. When analysts compare ratios across firms or over time, failure to account for these differences can lead to incorrect conclusions about profitability, efficiency, or risk. Financial management emphasizes adjusting or at least recognizing accounting differences to improve comparability and interpret ratios accurately. Option A correctly explains why caution is required, while the remaining options incorrectly assume uniformity or rigidity in accounting practices.
NEW QUESTION # 50
During the last year, Kretsmatt had the following cash flows:
* The firm had sales of $20,000 and net income of $5,000. Dividends of $1,000 were paid, and there were no changes to working capital accounts.
* The company purchased new equipment for $3,000. There were no sales of equipment and no depreciation expense recorded during the year.
* The company raised no funds through external financing and repaid no debt.
How much were Kretsmatt's net cash flows from financing for the year?
Answer: D
Explanation:
Cash flows from financing activities include transactions involving debt, equity, and cash distributions to owners. In this problem, the company did not raise any new external financing and did not repay any debt, so there are no financing inflows or outflows from borrowing or equity issuance. The only financing-related cash flow given is the payment of dividends of $1,000. Dividends paid are classified as a financing cash outflow because they represent a return of cash to shareholders rather than an operating or investing activity. The purchase of equipment is an investing activity, not a financing activity. Sales and net income relate primarily to operations, and the fact that working capital accounts did not change helps simplify the operating cash flow analysis, but it does not change the financing section. Therefore, net cash flow from financing equals negative
$1,000. This makes choice A correct. Financial statement analysis requires clear classification of cash flows into operating, investing, and financing categories so that analysts can understand how a firm generates cash, where it invests cash, and how it funds itself over time.
========
NEW QUESTION # 51
What is the relationship between the length of the cash cycle and the amount of cash a firm needs to operate?
Answer: B
Explanation:
The cash conversion cycle measures the time between cash outflows for production and cash inflows from customer payments. A longer cash cycle means that cash is tied up for a longer period in inventory and receivables before being recovered through sales. As a result, firms with longer cash cycles require larger cash balances or greater access to short-term financing to support ongoing operations. Financial managers aim to shorten the cash cycle by improving inventory turnover, accelerating collections, and managing payables efficiently. Option D correctly reflects this fundamental relationship emphasized in working capital management.
NEW QUESTION # 52
Why might tax expense on the income statement not reflect the actual taxes paid by a firm?
Answer: A
Explanation:
Tax expense reported on the income statement is calculated using accrual accounting, which recognizes revenues and expenses when they are earned or incurred, not necessarily when cash is paid. In contrast, actual taxes paid are based on tax laws and cash payments made to tax authorities. Differences arise due to temporary and permanent timing differences between financial reporting rules and tax regulations. Examples include depreciation methods, revenue recognition timing, loss carryforwards, and deferred tax assets or liabilities. These differences cause tax expense to diverge from cash taxes paid in a given period. Financial managers and analysts must understand this distinction to accurately assess cash flows, particularly when forecasting free cash flow or valuing firms. Option A correctly explains this discrepancy, whereas the other options either deny the existence of differences or incorrectly characterize tax expense accounting.
NEW QUESTION # 53
......
According to our investigation, the test syllabus of the Financial-Management exam is changing every year. Some new knowledge will be added into the annual real exam. Some old knowledge will be deleted. So you must have a clear understanding of the test syllabus of the Financial-Management study engine. Now, you can directly refer to our Financial-Management study materials. Because we have been in the field for over ten years and we are professional in this career. We can always offer the most updated information to our loyal customers.
Financial-Management Practice Test Online: https://www.passtorrent.com/Financial-Management-latest-torrent.html