2026 Latest ExamCost Accounting-for-Decision-Makers PDF Dumps and Accounting-for-Decision-Makers Exam Engine Free Share: https://drive.google.com/open?id=1gTh6HZ2YTvXoLEG-D9FvI-xI0SU2k7gm
WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) PDF dumps are the third and most convenient format of the WGU Accounting-for-Decision-Makers PDF questions prep material. This format is perfect for busy test takers who prefer to study for the WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) exam on the go. Questions bank in the ExamCost WGU Accounting-for-Decision-Makers Pdf Dumps is accessible via all smart devices. We also update WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) PDF questions regularly to ensure they match with the new content of the Accounting-for-Decision-Makers exam.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Cost Systems | 20–25% | - Cost concepts and classification
|
| Topic 2: Profit Planning | 10–15% | - Cost-volume-profit (CVP) analysis
|
| Topic 3: Budgeting and Decision Making | 10–15% | - Master budget and components
|
| Topic 4: Financial Analysis | 45–50% | - Purpose and components of financial statements
|
| Topic 5: Controls and Regulations | 10–15% | - Internal control systems and principles
|
>> PDF Accounting-for-Decision-Makers VCE <<
Almost no one likes boring study. Teachers and educationist have tried many ways to solve this problem. Arousing the interest might be the most effective method. So our company is focused on reforming preparation ways of the Accounting-for-Decision-Makers exam. Rigid memory is torturous and useless. Our Accounting-for-Decision-Makers Study Materials combine the knowledge with the new technology, which could greatly inspire your motivation. And if you click on our Accounting-for-Decision-Makers practice questions, you will feel the convenience.
NEW QUESTION # 41
How does management accounting differ from financial accounting?
Answer: D
Explanation:
The correct answer is A . The key difference is that management accounting is mainly used inside the organization for planning, control, performance evaluation, and decision-making, while financial accounting is aimed primarily at external users such as investors, creditors, and regulators. Management accounting reports are tailored to managers' needs and may include forecasts, budgets, cost analyses, and both financial and nonfinancial information.
Option B is incorrect because management accounting can absolutely help a company gain competitive advantage through pricing, efficiency analysis, budgeting, and strategic decision-making. Option C is misleading because "an unbiased view of economic performance" is more closely associated with external financial reporting. Option D is incorrect because management accounting is not restricted to financial data; it often includes nonfinancial measures such as production efficiency, quality metrics, customer behavior, and operational performance. This flexibility is one of its main strengths. Therefore, the best distinction is that management accounting is used primarily for internal planning, control, and evaluation , making Option A correct.
NEW QUESTION # 42
Which role do ethical standards have in management accounting?
Answer: C
Explanation:
The correct answer is D . In management accounting, ethical standards are intended to guide behavior and help resolve ethical dilemmas that professionals may encounter in practice. The IMA Statement of Ethical Professional Practice explains that its principles and standards serve as a guide for ethical conduct in management accounting and include guidance for the resolution of ethical conflict .
Option A is incorrect because ethical standards cannot predict with certainty whether another person will behave ethically. Option B is incorrect because the standards do not guarantee that a management accountant will work only with perfectly ethical companies. Option C is also incorrect because no code can prevent all unethical behavior by everyone involved. Instead, the standards provide a framework based on competence, confidentiality, integrity, and credibility so the accountant can respond appropriately when ethical issues arise.
Therefore, the most accurate role of ethical standards in management accounting is to provide guidance for addressing and resolving ethical conflicts in a professional, structured manner. That makes Option D the correct answer.
NEW QUESTION # 43
Which body regulates a certified public accounting firm's audit practices when the firm is auditing a large, publicly traded company?
Answer: B
Explanation:
The correct answer is D. The Public Company Accounting Oversight Board (PCAOB) . The PCAOB was created to oversee the audits of public companies and SEC-registered brokers and dealers in order to protect investors and support the public interest in accurate, independent audit reports. Its responsibilities include registration of audit firms, inspections, enforcement, and audit-related standard-setting. Because the question refers to a CPA firm auditing a large, publicly traded company , PCAOB oversight is the correct regulatory answer.
Option A is incorrect because FASB sets accounting standards, not audit practice regulation for public company auditors. Option B, FASAC , is an advisory council to FASB and does not regulate audit firms.
Option C, the IRS , administers tax laws and does not oversee external audit practices for public companies.
In accounting and auditing, it is essential to distinguish between those who set accounting rules and those who supervise auditors. For publicly traded companies, that audit oversight role belongs to the PCAOB , making Option D the only accurate choice.
NEW QUESTION # 44
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.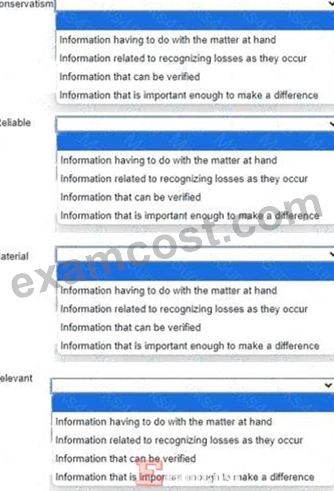
Answer:
Explanation: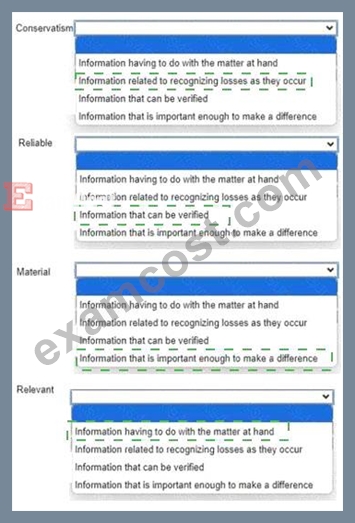
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 45
What would be the appropriate cost driver to allocate overhead for a call center?
Answer: A
Explanation:
The correct answer is B. Number of customer contacts . In a call center, overhead is driven primarily by the volume of customer interactions handled, so the most appropriate cost driver is the number of customer contacts or calls. Cost-per-call and contact-center cost analysis commonly use the number of calls or contacts as the central activity measure because those interactions consume staff time, telecom systems, and support resources.
Option A, total material cost , is not appropriate because call centers are service operations and usually do not consume direct materials in the way manufacturers do. Option C, total sales dollars , may be relevant for some selling analyses but does not directly measure the activity causing most call center overhead. Option D, number of labor hours , can sometimes be useful, but in this setting the more direct activity driver is the actual number of contacts handled. Since overhead in a call center tends to rise with customer interactions, the best allocation base is the number of customer contacts . Therefore, Option B is the correct answer.
NEW QUESTION # 46
......
The Accounting-for-Decision-Makers prep torrent we provide will cost you less time and energy. You only need relatively little time to review and prepare. After all, many people who prepare for the Accounting-for-Decision-Makers exam, either the office workers or the students, are all busy. The office workers are both busy in their jobs and their family life and the students must learn or do other things. But the Accounting-for-Decision-Makers Test Prep we provide are compiled elaborately and it makes you use less time and energy to learn and provide the study materials of high quality and seizes the focus the exam. It lets you master the most information and costs you the least time and energy.
Accounting-for-Decision-Makers Test Score Report: https://www.examcost.com/Accounting-for-Decision-Makers-practice-exam.html
BTW, DOWNLOAD part of ExamCost Accounting-for-Decision-Makers dumps from Cloud Storage: https://drive.google.com/open?id=1gTh6HZ2YTvXoLEG-D9FvI-xI0SU2k7gm