2026 IIA-CIA-Part3 Valid Test Fee | High Pass-Rate Valid IIA-CIA-Part3 Dumps: Internal Audit Function

P.S. Free 2026 IIA IIA-CIA-Part3 dumps are available on Google Drive shared by TestkingPass: https://drive.google.com/open?id=1H9AiltFuwkC1pJPFCHsE5hnsZ7mB71QH
In order to meet the requirements of our customers, Our IIA-CIA-Part3 test questions carefully designed the automatic correcting system for customers. It is known to us that practicing the incorrect questions is very important for everyone, so our IIA-CIA-Part3 exam question provide the automatic correcting system to help customers understand and correct the errors. Our IIA-CIA-Part3 Guide Torrent will help you establish the error sets. We believe that it must be very useful for you to take your IIA-CIA-Part3 exam, and it is necessary for you to use our IIA-CIA-Part3 test questions.
| Section | Weight | Objectives |
|---|
| Organizational Strategic Planning and Management | 25% | - Identify risk and control implications related to leadership and mentoring
- 1. Guiding people
- 2. Building organizational commitment
- 3. Coaching
- 4. Mentoring
- 5. Providing constructive feedback
- 6. Demonstrating entrepreneurial ability
- Identify the risk and control implications of different organizational structures
- 1. Centralized versus decentralized
- 2. Matrix structures
- 3. Flat versus traditional
- Examine organizational behavior and management principles
- 1. Change management
- 2. Conflict resolution
- 3. Motivation theories
- 4. Team dynamics
- 5. Leadership styles
- Examine how performance measures and controls are used to assess achievement of organizational objectives
- 1. Key performance indicators (KPIs)
- 2. Benchmarking
- 3. Balanced scorecard
- Analyze the organization's strategic planning process and its integration with the risk management strategy
- 1. Alignment to the organization's mission and values
- 2. Objective setting
- 3. Business context analysis
- 4. Alternative strategies evaluation
- 5. Control environment
- 6. Risk appetite definition
|
| Common Business Processes | 45% | - Describe the risk and control implications of supply chain management
- 1. Inventory management
- 2. Vendor management
- 3. Quality control
- Describe business processes and their risk and control implications
- 1. Logistics
- 2. Procurement
- 3. Product development
- 4. Sales and marketing
- 5. Human resources
- 6. Management of outsourced processes
- Recognize various forms and elements of contracts
- 1. Fixed-price and cost-reimbursable contracts
- 2. Consideration
- 3. Unilateral and bilateral contracts
- 4. Formality
- Examine financial management concepts and their risk and control implications
- 1. Financial accounting and reporting
- 2. Financial analysis and decision-making
- 3. Managerial accounting
- 4. Cost accounting
- 5. Capital budgeting and investment
- 6. Working capital management
- Identify risk and control implications of project management
- 1. Change management in projects
- 2. Project risk management
- 3. Time/team/resources/cost management
- 4. Project plan and scope
|
| Information Technology | 20% | - Recognize existing and emerging cybersecurity threats and vulnerabilities
- 1. Malware
- 2. Social engineering
- 3. Phishing
- 4. Ransomware
- Recognize data governance and data management concepts
- Explain the purpose and use of common information security and technology controls
- 1. Passwords
- 2. Firewalls
- 3. Biometrics
- 4. Antivirus
- 5. Multi-factor authentication
- 6. Encryption
- 7. Digital signatures
- 8. IT general controls
- Examine the role of data analytics in the audit process
- 1. Data extraction
- 2. Continuous auditing
- 3. Data analysis techniques
- Identify risk and control implications related to IT infrastructure and systems
- 1. Cloud computing
- 2. Operating systems
- 3. Networking
- 4. Business continuity and disaster recovery
- 5. Databases
- Recognize principles of data privacy and their potential impact on data security policies and practices
|
| Financial Management | 10% | - Examine the risk and control implications of financial statement analysis
- 1. Trend analysis
- 2. Ratio analysis
- 3. Common-size analysis
- Identify risk and control implications of financial management
- 1. Capital structure and financing
- 2. Financial instruments
- 3. Foreign currency
- 4. Working capital management
|
>> IIA-CIA-Part3 Valid Test Fee <<
Valid IIA-CIA-Part3 Dumps & IIA-CIA-Part3 Trustworthy Dumps
Instant answer feedback allows you to identify your vulnerabilities in a timely manner, so as to make up for your weaknesses. With our IIA-CIA-Part3 practice quiz, you will find that the preparation process is not only relaxed and joyful, but also greatly improves the probability of passing the IIA-CIA-Part3 Exam. And our pass rate of the IIA-CIA-Part3 training materials is high as 98% to 100%. You are bound to pass the exam if you buy our IIA-CIA-Part3 learning guide.
IIA Internal Audit Function Sample Questions (Q695-Q700):
NEW QUESTION # 695
What kind of strategy would be most effective for an organization to adopt in order to implement a unique advertising campaign for selling identical products across all of its markets?
- A. Multi-domestic strategy.
- B. Export strategy.
- C. Transnational strategy.
- D. Globalization strategy.
Answer: D
Explanation:
Comprehensive and Detailed In-Depth Explanation:
A globalization strategy focuses on standardizing products and marketing campaigns across all international markets. This ensures consistent branding and messaging, achieving economies of scale while maintaining a uniform customer experience.
Option A (Export strategy) primarily refers to selling domestic products abroad without a significant focus on global marketing.
Option B (Transnational strategy) balances global standardization and local adaptation, but does not emphasize a single advertising approach.
Option C (Multi-domestic strategy) tailors marketing and product offerings to each local market, making it less suitable for a uniform advertising campaign.
Thus, the globalization strategy (Option D) is the best approach for a unique yet standardized advertising campaign across markets.
Reference: IIA Business Acumen - Global Business Strategies
NEW QUESTION # 696
When applied to international economics, the theory of comparative advantage proposes that total worldwide output will be greatest when:
- A. Each nation's total imports approximately equal its total exports.
- B. Goods that contribute to a nation's balance-of-payments deficit are no longer imported.
- C. Each good is produced by the nation that has the lowest opportunity cost for that good.
- D. International trade is unrestricted and tariffs are not imposed.
Answer: C
NEW QUESTION # 697
Which of the following is the most appropriate action an internal auditor would perform during an audit of his organization ' s IT change management process?
- A. Publish a schedule that lists all approved changes and planned implementation dates.
- B. Perform a risk assessment to determine the likelihood that risk could occur due to insufficient patch application.
- C. Update change management processes on a consistent basis to keep up with changing technologies.
- D. Validate that only authorized personnel can migrate changes into the production environment.
Answer: D
Explanation:
During an audit of IT change management, the internal auditor should validate whether only authorized personnel can migrate changes into production. This directly tests segregation of duties, authorization, and production environment protection. Option B may be relevant in a patch management review, but it is narrower and not the most direct change management audit action. Option C is a management activity, not an internal audit responsibility. Option D is also management's responsibility because internal audit should not update operating processes it may later audit. Effective change management requires proper request approval, testing, migration control, emergency change review, and post-implementation monitoring. Therefore, Option A is correct.
NEW QUESTION # 698
Company J produces two components: A-1 and A-2. The unit throughput contribution margins for A-1 and A-2 are US $150 and US $300, respectively. Each component must proceed through two processes: Operation 1 and Operation 2. The capacity of Operation 1 is 180 machine hours, with A-1 and A-2 requiring 1 hour and 3 hours, respectively.
Furthermore, Company J can sell only 45 units of A-1 and 100 units of A-2. However,
Company J is considering expanding Operation 1's capacity by 90 machine hours at a cost of US $80 per hour. Assuming that Operation 2 has sufficient capacity to handle any additional output from Operation 1, how much should Company J produce?
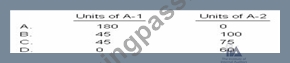
- A. Option D
- B. Option A
- C. Option C
- D. Option C
Answer: D
Explanation:
A-1's throughput contribution margin per unit of the scarce resource the internal binding constraint) is US $150 $150 UCM - 1 machining hour). A-2's throughput contribution margin per unit of the scarce resource is U $100 $300 UCM - 3 machine hours).
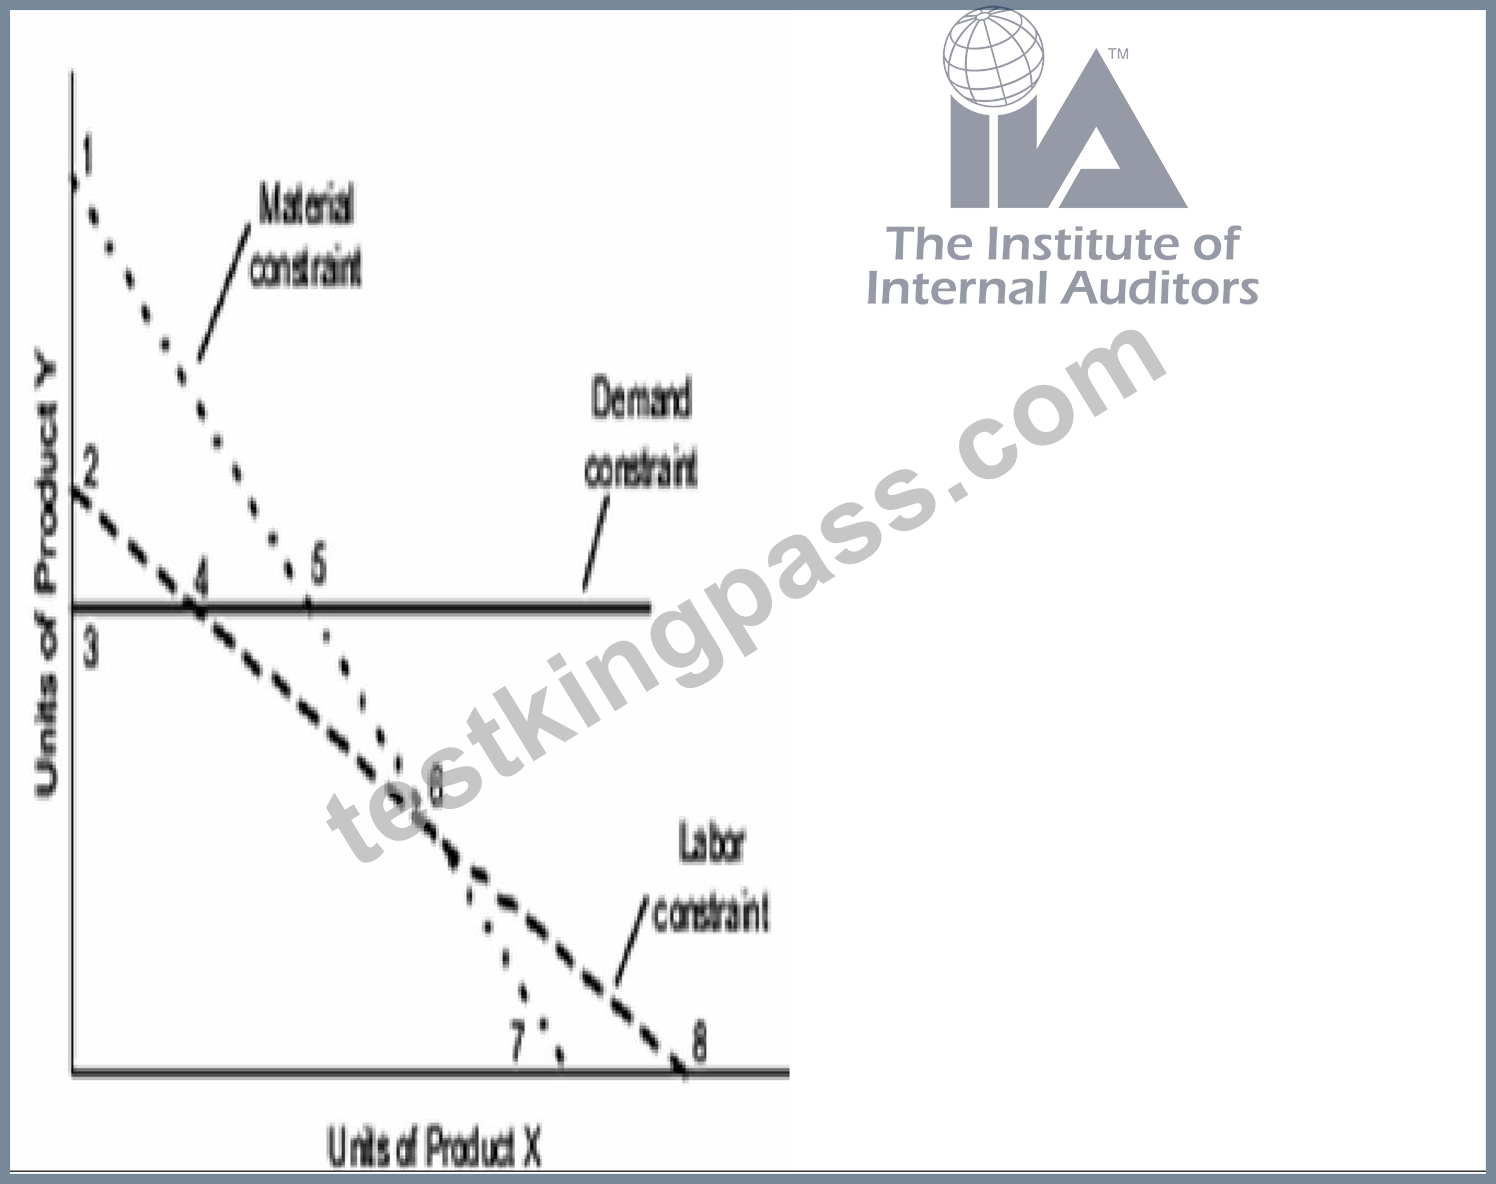
Consequently, Company J should produce as much A-1 as it can sell 45 units). If Company adds 90 machine hours to increase the capacity of Operation -I to 270 hours 180 + 90), it cannot produce additional units of A-1 because the external binding constraint has not been relaxed. However, it can produce additional units of A-2. Given that the UCM per machine hour of A-2 is U $100 and that the cost is US $80 per hour, adding capacity to Operation 1 is profitable. Thus, Company J should use 45 machine hours to produce 45 units of A-1. The remaining 225 machine hours 270 - 45) should be used to produce 75 units 225 - 3 hours) of A-2. The latter amount is within the external binding constraint. A company produces two products, and Y, which use material and labor as inputs. Fixed amounts of labor and material are available for production each month In addition. the demand for product Y each month is limited: product has no constraint an the number of units that can be sold. A graphical depiction of these production and demand constraints is presented in the opposite column.
NEW QUESTION # 699
Which of the following statements is true regarding cost-volume-profit analysis?
- A. Contribution margin is the amount remaining from sales revenue after fixed expenses have been deducted.
- B. Breakeven point is the amount of units sold to cover variable costs.
- C. Following breakover1, he operating income will increase by the excess of fixed costs less the variable costs per units sold.
- D. Breakeven occurs when the contribution margin covers fixed costs.
Answer: D
Explanation:
Cost-Volume-Profit (CVP) analysis is used to determine how changes in costs and volume affect a company's operating profit.
* Correct Answer (C - Breakeven Occurs When the Contribution Margin Covers Fixed Costs)
* Contribution Margin (CM) = Sales Revenue - Variable Costs.
* The breakeven point is where total contribution margin equals total fixed costs, meaning the company has no profit or loss.
* The IIA's Practice Guide: Auditing Financial Performance supports this as the key breakeven definition.
* Why Other Options Are Incorrect:
* Option A (Contribution margin is the amount remaining after fixed expenses are deducted):
* Incorrect because CM is calculated before fixed expenses are subtracted.
* Option B (Breakeven point is the amount of units sold to cover variable costs):
* Incorrect because breakeven covers fixed costs as well, not just variable costs.
* Option D (Following breakeven, operating income increases by the excess of fixed costs less variable costs per unit sold):
* Incorrect because operating income increases by the contribution margin per unit, not by the difference between fixed and variable costs.
* IIA Practice Guide: Auditing Financial Performance - Defines breakeven analysis as when contribution margin covers fixed costs.
* IIA GTAG 13: Business Performance - Discusses cost-volume-profit analysis for financial decision- making.
IIA References for Validation:Thus, C is the correct answer because breakeven occurs when the contribution margin equals fixed costs.
NEW QUESTION # 700
......
We will provide you with three different versions of our IIA-CIA-Part3 exam questions. The PDF version allows you to download our IIA-CIA-Part3 quiz prep. After you download the PDF version of our learning material, you can print it out. In this way, you can learn our IIA-CIA-Part3 quiz prep on paper. We believe that it will be more convenient for you to take notes. Our website is a very safe and regular platform. You can download our IIA-CIA-Part3 Exam Guide with assurance. You can take full advantage of the fragmented time to learn, and eventually pass the authorization of IIA-CIA-Part3 exam.
Valid IIA-CIA-Part3 Dumps: https://www.testkingpass.com/IIA-CIA-Part3-testking-dumps.html
- Reliable IIA-CIA-Part3 Dumps ✍ IIA-CIA-Part3 Latest Exam Duration 👽 IIA-CIA-Part3 Pdf Demo Download 🤛 Open ▶ www.testkingpass.com ◀ enter ➠ IIA-CIA-Part3 🠰 and obtain a free download 👫IIA-CIA-Part3 New Dumps Sheet
- Earn the Credential of IIA IIA-CIA-Part3 Exam ⛰ ⮆ www.pdfvce.com ⮄ is best website to obtain 「 IIA-CIA-Part3 」 for free download 🔅Exam IIA-CIA-Part3 Review
- 100% IIA-CIA-Part3 Accuracy 👍 IIA-CIA-Part3 Latest Exam Duration 😲 IIA-CIA-Part3 Braindump Pdf ⬅️ Open website ➡ www.examcollectionpass.com ️⬅️ and search for 《 IIA-CIA-Part3 》 for free download 🍕IIA-CIA-Part3 Latest Exam Duration
- IIA-CIA-Part3 Labs 🙏 Exam IIA-CIA-Part3 Review 🤕 IIA-CIA-Part3 Practice Test Engine 🏡 Search for 【 IIA-CIA-Part3 】 and obtain a free download on 「 www.pdfvce.com 」 ✒Test IIA-CIA-Part3 Questions Pdf
- Test IIA-CIA-Part3 Question 🔷 IIA-CIA-Part3 Latest Exam Duration 🕡 Test IIA-CIA-Part3 Questions Pdf ⏪ Search for ( IIA-CIA-Part3 ) and download it for free immediately on ⮆ www.practicevce.com ⮄ 🎳IIA-CIA-Part3 Exam Preparation
- IIA-CIA-Part3 exam resources - IIA-CIA-Part3 test prep - IIA-CIA-Part3 pass score 🥬 Open ▷ www.pdfvce.com ◁ and search for ⏩ IIA-CIA-Part3 ⏪ to download exam materials for free 🎸IIA-CIA-Part3 Reliable Test Questions
- IIA-CIA-Part3 Labs 🥅 IIA-CIA-Part3 Valid Test Sample 😄 Exam IIA-CIA-Part3 Review 🍨 Go to website ➽ www.pdfdumps.com 🢪 open and search for ▷ IIA-CIA-Part3 ◁ to download for free 🎑Test IIA-CIA-Part3 Questions Pdf
- Valid IIA-CIA-Part3 Valid Test Fee - Leader in Certification Exams Materials - Free Download Valid IIA-CIA-Part3 Dumps 🙏 Immediately open ⮆ www.pdfvce.com ⮄ and search for ➠ IIA-CIA-Part3 🠰 to obtain a free download 🍫IIA-CIA-Part3 Valid Test Sample
- Exam IIA-CIA-Part3 Review 🔴 Test IIA-CIA-Part3 Questions Pdf 🧒 Reliable IIA-CIA-Part3 Dumps 🅰 Search for ( IIA-CIA-Part3 ) and download it for free immediately on ➠ www.examdiscuss.com 🠰 💕100% IIA-CIA-Part3 Accuracy
- Test IIA-CIA-Part3 Questions Pdf 🚡 IIA-CIA-Part3 Valid Test Sample 🌜 IIA-CIA-Part3 Exam Labs 📑 Search for 《 IIA-CIA-Part3 》 and download it for free on ▶ www.pdfvce.com ◀ website 💬IIA-CIA-Part3 Exam Questions Fee
- IIA-CIA-Part3 Exam Questions Fee 👗 Test IIA-CIA-Part3 Question 🔊 IIA-CIA-Part3 Latest Study Plan 🍄 ➤ www.examdiscuss.com ⮘ is best website to obtain ⏩ IIA-CIA-Part3 ⏪ for free download 🎶IIA-CIA-Part3 Latest Study Plan
- mooc.ifro.edu.br, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, learn.csisafety.com.au, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, Disposable vapes
P.S. Free & New IIA-CIA-Part3 dumps are available on Google Drive shared by TestkingPass: https://drive.google.com/open?id=1H9AiltFuwkC1pJPFCHsE5hnsZ7mB71QH